Global Military Land Vehicles Market: Size, Share, Demand & Future Growth 2026–2034
Military Land Vehicles Market Size, Share & Demand Report By Type, Application, Region & Forecast 2026–2034
Market Overview
The Military Land Vehicles Market is experiencing steady growth as defense forces increasingly focus on modernization, advanced combat capabilities, mobility, protection, and operational effectiveness. Military land vehicles include main battle tanks, armored personnel carriers, infantry fighting vehicles, and tactical trucks designed to support combat, transportation, reconnaissance, surveillance, peacekeeping, and homeland security operations.
The global production of military land vehicles remained robust, with an estimated 45,000 units manufactured in 2025 across all categories. Main Battle Tanks accounted for approximately 32% of the total market share, followed by Armored Personnel Carriers with 28%, Infantry Fighting Vehicles with 22%, and Tactical Trucks with 18%. The market is supported by increasing geopolitical tensions, growing defense modernization programs, rising defense budgets, and demand for advanced combat and tactical vehicles.
Request Sample Link:
https://reedintelligence.com/market-analysis/military-land-vehicles-market/request-sample
Market Size and Forecast
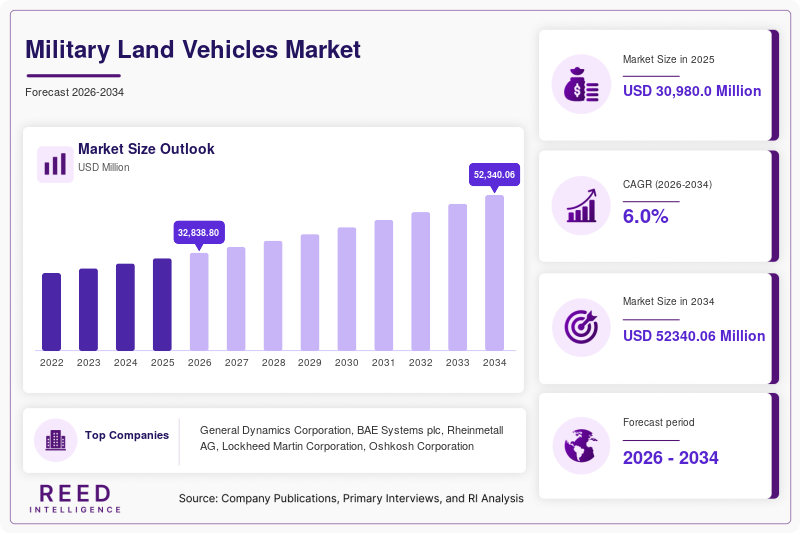
The Military Land Vehicles Market size is projected at USD 32,850.0 million in 2026 and is expected to reach USD 52,340.06 million by 2034. The market is forecast to expand at a CAGR of 6.0% during the forecast period.
Market development is closely linked to increasing defense spending, modernization programs, regional security concerns, and the replacement of aging military vehicle fleets with advanced platforms. The market is also witnessing increased integration of advanced technologies designed to improve lethality, survivability, situational awareness, mobility, and operational effectiveness.
North America currently leads the global market with a 38% share, while Asia-Pacific is projected to record the fastest CAGR of 7.8% through 2034. India is projected to reach USD 5,850.0 million by 2034, expanding at a CAGR of 8.5%.
Market Drivers
Increasing Geopolitical Tensions
Increasing geopolitical tensions and regional conflicts worldwide are a major driver of the Military Land Vehicles Market. Global defense spending exceeded USD 2.2 trillion in 2025, supporting investments in modern combat platforms, tactical vehicles, and advanced military equipment.
Defense Modernization Programs
Defense modernization programs across major economies are contributing significantly to market expansion. Countries are investing in replacing aging vehicle fleets with advanced platforms equipped with improved armor, firepower, mobility, electronics, and protection systems.
Rising Demand for Advanced Combat Vehicles
The growing demand for advanced combat and tactical vehicles is supporting market growth. Main battle tanks, infantry fighting vehicles, and armored personnel carriers remain important components of modern ground forces, while tactical trucks continue to support logistics and transportation requirements.
Increasing Focus on Homeland Security
The increasing focus on homeland security, border protection, and regional security is creating additional demand for military land vehicles. Emerging economies are also increasing investments in military vehicle fleets in response to regional security concerns and territorial disputes.
Advanced Technology Integration
The adoption of AI-enabled targeting systems and autonomous navigation features has increased by 25% year-over-year, with more than 40% of new vehicle programs incorporating these technologies. Active protection systems, advanced armor solutions, and integrated electronic warfare capabilities are also becoming important areas of vehicle development.
Market Challenges
High Development and Procurement Costs
The high costs associated with developing and procuring advanced military vehicles can place pressure on defense budgets. Complex technologies, advanced protection systems, and specialized components can increase overall vehicle acquisition costs.
Lengthy Procurement Cycles
Lengthy procurement cycles and complex acquisition processes can delay vehicle deliveries and affect the pace of market expansion. Military vehicle programs often involve extensive development, testing, procurement, and integration requirements.
Political and Export Restrictions
Political restrictions and export controls can limit international sales and technology transfers. Such restrictions can affect manufacturers seeking to expand military vehicle programs across international markets.
Competition from Alternative Warfare Capabilities
Alternative warfare capabilities, including drones and missiles, can influence defense priorities and investment decisions. The availability of these technologies may affect the allocation of defense resources toward traditional land vehicle programs.
Market Opportunities
Autonomous and Remotely Operated Vehicles
The development of autonomous and remotely operated military vehicles represents an important opportunity for the market. These platforms can support operational capabilities while reducing risk to personnel and enabling new approaches to military missions.
Modular and Upgradeable Platforms
Modular and upgradeable vehicle platforms provide opportunities for manufacturers to address evolving mission requirements. Vehicles designed with adaptable architectures can support the integration of new technologies and capabilities over time.
Advanced Materials
The application of advanced materials for lightweight armor and improved protection offers additional opportunities. Manufacturers can focus on improving vehicle protection while addressing mobility and operational requirements.
Growing Demand in Emerging Markets
Increasing defense budgets and regional security concerns in emerging markets are creating opportunities for military land vehicle manufacturers. Growing modernization initiatives can support demand for combat, transportation, logistics, and support vehicles.
Market Segmentation
The Military Land Vehicles Market is segmented by Type and Application. By Type, Main Battle Tanks dominate with a 32% market share, followed by Armored Personnel Carriers at 28%, Infantry Fighting Vehicles at 22%, and Tactical Trucks at 18%. By Application, Combat Operations dominates with 45%, followed by Transportation & Logistics at 28%, Reconnaissance & Surveillance at 15%, and Peacekeeping & Homeland Security at 12%.
By Type
Main Battle Tanks
Main Battle Tanks represent the largest segment in the Military Land Vehicles Market, commanding a 32% share, with revenue exceeding USD 9,300 million in 2025. These heavily armored combat vehicles feature powerful main guns and advanced fire control systems. Key technical specifications include armor protection, firepower, mobility, and advanced electronics. Demand is driven by combat operations and ongoing modernization programs.
Armored Personnel Carriers
Armored Personnel Carriers capture a 28% share of the market, with revenue of USD 8,138 million in 2025. These armored vehicles are designed to transport infantry troops safely to and from combat zones. Important characteristics include carrying capacity, armor protection, and mobility. Demand is supported by troop transportation and protected mobility missions.
Infantry Fighting Vehicles
Infantry Fighting Vehicles represent 22% of the market, with revenue of USD 6,394 million in 2025. These tracked or wheeled vehicles provide transportation and fire support for infantry. Key specifications include armament, armor, and dismount capacity. Their demand is driven by the requirement for direct fire support and infantry mobility.
Tactical Trucks
Tactical Trucks account for 18% of the market, with revenue of USD 5,232 million in 2025. These vehicles are designed for logistics, transportation, and support operations. Payload capacity, off-road mobility, and durability are important characteristics. Demand is driven by the need to transport supplies, equipment, and personnel across operational environments.
By Application
Combat Operations
Combat Operations dominate the application segment with 45% of sales, representing USD 13,082 million in 2025. This segment includes military vehicles used in direct combat roles, particularly main battle tanks and infantry fighting vehicles. Usage penetration exceeds 70% in active military operations, with firepower, protection, and mobility being key characteristics.
Transportation & Logistics
Transportation & Logistics accounts for 28% of the market, with revenue of USD 8,138 million in 2025. The segment includes vehicles used to transport troops, supplies, and equipment. Demand is supported by the need for efficient logistical support, with payload capacity, reliability, and fuel efficiency serving as important characteristics.
Reconnaissance & Surveillance
Reconnaissance & Surveillance represents 15% of the market, with revenue of USD 4,360 million in 2025. This segment includes specialized vehicles used for intelligence gathering and battlefield observation. Growth is supported by increasing emphasis on situational awareness and intelligence-led operations, with stealth, sensor integration, and communications capabilities being important characteristics.
Peacekeeping & Homeland Security
Peacekeeping & Homeland Security accounts for 12% of the market, with revenue of USD 3,488 million in 2025. The segment includes military vehicles used for domestic security, border protection, and peacekeeping missions. Demand is supported by the need for versatile vehicles suitable for diverse operational environments.
Regional Analysis
North America
North America leads the Military Land Vehicles Market with a 38% share and revenue of USD 11,041 million in 2025. The United States accounts for 88% of regional demand, supported by its large defense budget, ongoing modernization programs, and investment in next-generation combat vehicles. The regional market emphasizes technological superiority and advanced capabilities.
Europe
Europe represents the second-largest market, capturing a 28% share with revenue of USD 8,138 million in 2025. Germany, France, and the United Kingdom collectively account for 60% of regional demand. Growth is supported by increased defense spending, regional security concerns, modernization of aging vehicle fleets, collaborative procurement programs, and technological innovation.
Asia-Pacific
Asia-Pacific accounts for 24% of the global Military Land Vehicles Market, with revenue of USD 6,975 million in 2025. China, India, and Japan account for 65% of regional demand. The regional market is projected to grow at the fastest CAGR of 7.8% through 2034, supported by rising defense budgets, regional tensions, large-scale modernization programs, and indigenous manufacturing capabilities.
Latin America and Middle East & Africa
Latin America and Middle East & Africa together account for the remaining 10% of the Military Land Vehicles Market, with Brazil and Saudi Arabia leading their respective regions. Both regions are projected to grow at CAGRs exceeding 6.5%, driven by regional security concerns, growing defense budgets, and modernization initiatives.
Key Players
-
General Dynamics Corporation
-
BAE Systems plc
-
Rheinmetall AG
-
Lockheed Martin Corporation
-
Oshkosh Corporation
-
Northrop Grumman Corporation
-
Krauss-Maffei Wegmann GmbH & Co. KG
-
Navistar Defense
Other companies operating in the Military Land Vehicles Market include AM General LLC, Rosenbauer International AG, Hanwha Defense, Hyundai Rotem Company, Norinco (China North Industries Corporation), Textron Inc., and Renault Trucks Defense (Arquus).
Recent Developments
In April 2026, General Dynamics Land Systems unveiled a new variant of the Abrams main battle tank with enhanced active protection systems and improved mobility.
In June 2025, Rheinmetall AG announced a major contract for the delivery of new Lynx infantry fighting vehicles to a European customer.
In August 2025, BAE Systems plc launched a new generation of armored personnel carriers with hybrid-electric drive technology for reduced fuel consumption.
In February 2026, Oshkosh Corporation introduced a new tactical truck with autonomous convoy capabilities and enhanced payload capacity.
In October 2025, Hyundai Rotem Company secured a contract to supply advanced main battle tanks to a Southeast Asian nation, marking a significant export win.
Conclusion
The Military Land Vehicles Market is projected to grow from USD 32,850.0 million in 2026 to USD 52,340.06 million by 2034 at a CAGR of 6.0%. Increasing geopolitical tensions, defense modernization programs, rising demand for advanced combat and tactical vehicles, and continued investment in next-generation military technologies will support market expansion.
Main Battle Tanks currently lead the type segment with a 32% share, while Combat Operations leads applications with 45%. North America remains the largest regional market with a 38% share, while Asia-Pacific is projected to record the fastest CAGR of 7.8% through 2034.
Overall, the Military Land Vehicles Market continues to present opportunities across autonomous and remotely operated vehicles, modular platforms, advanced materials, hybrid-electric propulsion, and next-generation combat technologies as military forces focus on modernization, protection, mobility, and operational capabilities.
Report Link:
https://reedintelligence.com/market-analysis/military-land-vehicles-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
