Dental Sleep Medicine Market Outlook: Growth Drivers, Trends & Emerging Opportunities 2026–2034
Dental Sleep Medicine Market Size, Share, Demand, Growth & Forecast 2026–2034
Market Overview
The Dental Sleep Medicine Market is experiencing strong growth as the prevalence of obstructive sleep apnea and sleep-related breathing disorders increases and awareness of non-invasive treatment options expands. Dental sleep medicine encompasses dental devices and therapeutic solutions designed to treat conditions including obstructive sleep apnea (OSA), snoring, and bruxism. Key products include oral appliances, mandibular advancement devices, and tongue retaining devices that help maintain an open airway during sleep.
The dental sleep medicine market is supported by increasing awareness among dentists and patients, growing demand for alternatives to CPAP therapy, and advances in digital dentistry and customized oral appliances. Globally, an estimated 2.5 million oral appliances were prescribed in 2025. Mandibular Advancement Devices accounted for approximately 52% of the total market share, followed by Tongue Retaining Devices at 28% and Oral Appliances for snoring and bruxism at 20%.
Request Sample Link:
https://reedintelligence.com/market-analysis/dental-sleep-medicine-market/request-sample
Market Size and Forecast
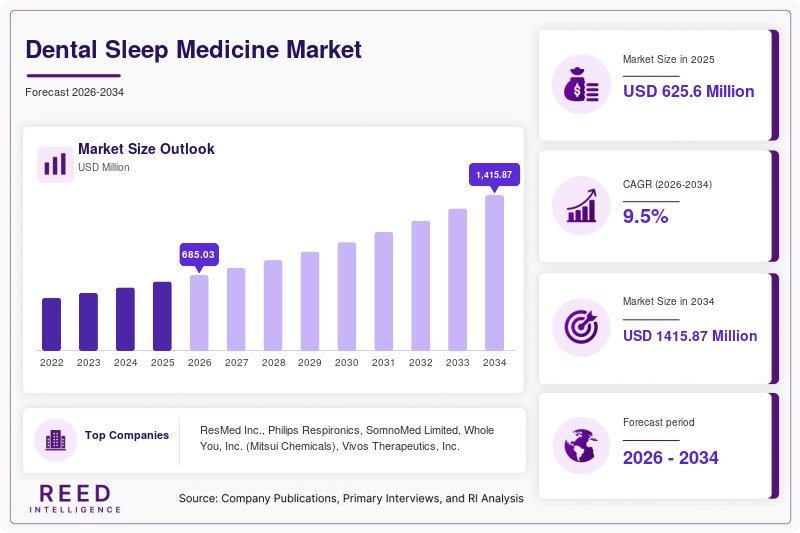
The dental sleep medicine market size is projected at USD 685.0 million in 2026 and is expected to hit USD 1,415.87 million by 2034, expanding at a CAGR of 9.5% during the forecast period.
North America currently leads the market with a 45% share, while Asia-Pacific is projected to be the fastest-growing regional market, with a CAGR of 12.5% through 2034. The market's expansion is closely associated with the increasing prevalence of obstructive sleep apnea, growing dental infrastructure, and rising adoption of oral appliance therapy.
Mandibular Advancement Devices remain the dominant product segment with a 52% share, while Sleep Apnea represents the leading application segment with a 65% share. China is projected to reach USD 125.0 million by 2034, expanding at a CAGR of 14.2%.
Market Drivers
Increasing Prevalence of Obstructive Sleep Apnea
The increasing global prevalence of obstructive sleep apnea is a major driver of the dental sleep medicine market. OSA affects an estimated 1 billion people worldwide, with over 80% of cases undiagnosed. Growing recognition of sleep-related breathing disorders is increasing demand for diagnosis and treatment solutions.
Rising Demand for Non-Invasive Treatment
The growing demand for non-invasive alternatives to CPAP therapy is supporting market expansion. Oral appliance therapy provides an alternative treatment approach, particularly for patients with mild to moderate OSA and individuals who cannot tolerate CPAP therapy.
Growing Awareness Among Dentists and Patients
Increasing awareness about the connection between dental health and sleep disorders is creating additional market opportunities. More dental professionals are seeking training and certification in dental sleep medicine, while patients are becoming increasingly aware of available treatment options.
Growing Role of Dentists in Sleep Disorder Screening
The recognition of dentists' role in identifying and screening patients for sleep disorders is expanding the addressable market. Greater integration between dental professionals and sleep medicine providers is supporting broader adoption of dental sleep medicine solutions.
Market Challenges
Limited Awareness
Limited awareness about dental sleep medicine among the general public and primary care physicians can delay diagnosis and treatment. This creates a challenge for broader adoption of dental sleep medicine services.
Insurance and Reimbursement Constraints
Variability in insurance coverage and reimbursement for oral appliance therapy can restrict patient access. Differences in reimbursement practices may affect the adoption of dental sleep medicine solutions across markets.
Competition from CPAP Therapy
CPAP therapy remains the gold standard for severe obstructive sleep apnea, creating competitive pressure for dental sleep medicine solutions in certain patient populations.
Training and Certification Requirements
The lack of standardized training and certification requirements across different regions can create variability in the delivery of dental sleep medicine services. Continuous education and training remain important for maintaining quality of care.
Market Opportunities
Screening and Diagnosis
The expanding screening and diagnosis segment presents opportunities for dental professionals to identify patients with sleep disorders and refer them for appropriate care. Greater involvement of dentists in sleep disorder screening can expand the use of dental sleep medicine solutions.
Advanced Oral Appliances
The development of advanced oral appliances with improved comfort and efficacy represents another significant opportunity. Innovations in customized devices can support patient adherence and therapeutic outcomes.
Digital Dentistry and 3D Printing
Digital dentistry and 3D printing are creating opportunities for customized dental sleep medicine products. Digital scanning, CAD/CAM design, and 3D printing enable precise fabrication of mandibular advancement devices. Adoption of digital workflows has increased by 35% year-over-year, with more than 45% of new oral appliances fabricated using digital processes.
Telemedicine and Remote Monitoring
Telemedicine and remote monitoring provide opportunities to make dental sleep medicine more convenient and accessible. These technologies can support patient management and monitoring while expanding access to specialized services.
Market Segmentation
The Dental Sleep Medicine Market is segmented by Product and Application. By Product, Mandibular Advancement Devices lead with a 52% market share, followed by Tongue Retaining Devices at 28% and Oral Appliances for Snoring and Bruxism at 20%. By Application, Sleep Apnea dominates with a 65% share, followed by Snoring at 22% and Bruxism at 13%.
By Product
Mandibular Advancement Devices
Mandibular Advancement Devices represent the largest product segment, commanding a 52% share, with revenue exceeding USD 356 million in 2025. These devices reposition the lower jaw forward to help keep the airway open during sleep. The segment is driven by its use in treating mild to moderate obstructive sleep apnea and its acceptance among patients who cannot tolerate CPAP.
Tongue Retaining Devices
Tongue Retaining Devices capture a 28% share, with revenue of USD 192 million in 2025. These devices use suction to hold the tongue forward and prevent it from blocking the airway. Demand is supported by their use among patients with specific anatomical considerations or those who do not respond to mandibular advancement devices.
Oral Appliances for Snoring and Bruxism
Oral Appliances for Snoring and Bruxism account for 20% of the market, generating revenue of USD 137 million in 2025. This segment includes snoring mouthpieces and bruxism guards designed to reduce snoring and protect teeth from grinding and clenching.
By Application
Sleep Apnea
Sleep Apnea dominates the application segment with 65% of sales, representing USD 445 million in 2025. The segment focuses on oral appliance treatment for mild to moderate obstructive sleep apnea. Usage penetration exceeds 35% among diagnosed OSA patients in developed markets.
Snoring
Snoring accounts for 22% of the market, with revenue of USD 151 million in 2025. Increasing awareness of the social and health impacts of snoring is supporting demand for oral appliances focused on comfort and effectiveness.
Bruxism
Bruxism represents 13% of the market, with revenue of USD 89 million in 2025. The segment includes oral appliances designed to protect teeth from grinding and clenching during sleep, with demand supported by increasing awareness of the dental consequences of bruxism.
Regional Analysis
North America
North America leads the Dental Sleep Medicine Market with a 45% share and revenue of USD 308 million in 2025. The United States accounts for 90% of regional demand, supported by high prevalence of sleep apnea, advanced dental infrastructure, and strong awareness of dental sleep medicine. The regional market emphasizes innovation, comprehensive care, and integration with sleep medicine networks.
Europe
Europe represents the second-largest market, capturing a 30% share with revenue of USD 206 million in 2025. Germany, the United Kingdom, and France collectively account for 58% of regional demand. Well-established healthcare systems and increasing awareness of sleep disorders contribute to market growth.
Asia-Pacific
Asia-Pacific accounts for 18% of the global market, with revenue of USD 123 million in 2025. China, Japan, and India account for 65% of regional demand. The region is projected to grow at the fastest CAGR of 12.5% through 2034, supported by healthcare investment, expanding dental infrastructure, and rising awareness of dental sleep medicine.
Latin America and Middle East & Africa
Latin America and the Middle East & Africa together account for the remaining 7% of the market. Brazil and the UAE lead their respective regions. Both regions are projected to grow at CAGRs exceeding 11%, supported by improving dental infrastructure and growing awareness of sleep disorders.
Key Players
-
ResMed Inc.
-
Philips Respironics
-
SomnoMed Limited
-
Whole You, Inc. (Mitsui Chemicals)
-
Vivos Therapeutics, Inc.
-
ProSomnus Sleep Technologies
-
Panthera Dental
-
Oventus Medical
Other companies operating in the market include Airway Management, Inc., Apnea Sciences Corporation, Braebon Medical Corporation, Klearway (Airway Management), AM Align, OraLux, and Myofunctional Research Co.
Recent developments include SomnoMed Limited's April 2026 launch of a 3D-printed mandibular advancement device with enhanced customization and patient comfort features. In June 2025, ResMed Inc. announced a partnership with a leading dental network to expand access to oral appliance therapy for sleep apnea patients. In August 2025, Vivos Therapeutics received FDA clearance for a new oral appliance designed to treat obstructive sleep apnea by remodeling the airway. ProSomnus Sleep Technologies introduced precision oral appliances with integrated remote monitoring capabilities in February 2026, while Panthera Dental launched a digital workflow for dental sleep medicine in October 2025.
Conclusion
The Dental Sleep Medicine Market is projected to grow from USD 685.0 million in 2026 to USD 1,415.87 million by 2034 at a CAGR of 9.5%. Increasing prevalence of obstructive sleep apnea, rising demand for non-invasive treatment alternatives, growing awareness among dentists and patients, and advances in digital dentistry are supporting market expansion.
Mandibular Advancement Devices currently lead the product segment with a 52% share, while Sleep Apnea leads applications with 65%. North America remains the largest regional market with a 45% share, while Asia-Pacific is projected to record the fastest CAGR of 12.5% through 2034.
The Dental Sleep Medicine Market continues to present opportunities across advanced oral appliances, digital dentistry, 3D printing, screening and diagnosis, telemedicine, and remote monitoring as demand for accessible and non-invasive sleep disorder treatment solutions increases.
Report Link:
https://reedintelligence.com/market-analysis/dental-sleep-medicine-market
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
