Independent Software Vendors Market 2026–2034: SaaS, AI Agents, Cloud Marketplaces & Emerging Opportunities
Independent Software Vendors Market Size, Share, Demand, Growth & Forecast 2026–2034
Market Overview
The Independent Software Vendors Market is expanding as software providers increasingly shift from standalone software-selling models toward ecosystem-based distribution, cloud marketplaces, SaaS delivery, embedded applications, and AI-enabled software. Independent Software Vendors (ISVs) are increasingly using hyperscaler and enterprise-platform ecosystems to reach customers, simplify procurement, and integrate products directly into existing technology environments.
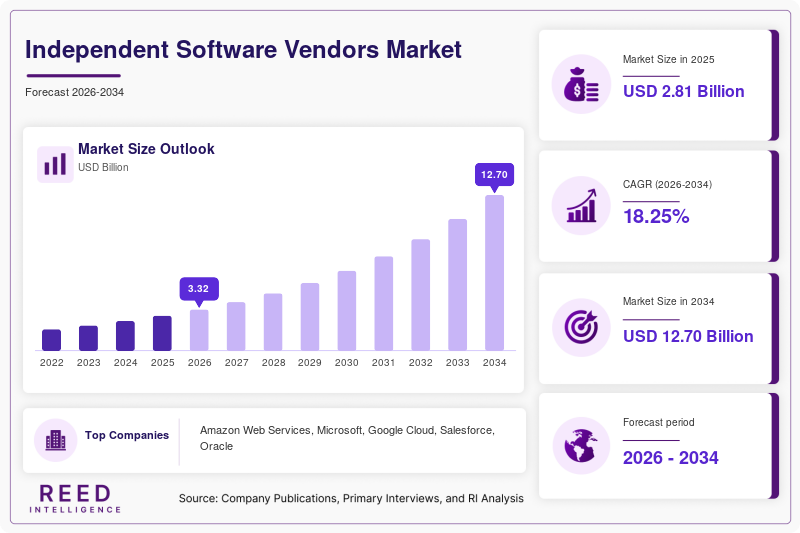
The independent software vendors market was valued at USD 2.81 billion in 2025 and is projected to grow from USD 3.32 billion in 2026 to USD 12.70 billion by 2034. The market is supported by cloud marketplaces, recurring SaaS models, AI applications, partner ecosystems, and increasing demand for specialized enterprise software.
Request Sample Link:
https://reedintelligence.com/market-analysis/independent-software-vendors-market/request-sample
Market Size and Forecast
The Independent Software Vendors Market is projected to reach USD 3.32 billion in 2026, compared with USD 2.81 billion in 2025, and is expected to reach USD 12.70 billion by 2034. The market is forecast to register a CAGR of 18.25% during 2026–2034.
The market is increasingly connected to cloud procurement and enterprise technology ecosystems. AWS Marketplace, Microsoft Marketplace, and Google Cloud Marketplace provide mechanisms for ISVs to publish and sell software through established cloud procurement channels.
Cloud marketplace infrastructure is also becoming increasingly important for enterprise transactions. Microsoft allows eligible Marketplace purchases to count toward Azure consumption commitments, while AWS and Google Cloud provide marketplace-based billing and procurement mechanisms.
Market Drivers
Cloud Marketplaces Are Turning Enterprise Procurement Into a Scalable Distribution Channel
Cloud marketplaces are increasingly functioning as procurement infrastructure rather than simple software catalogs. AWS enables ISVs to offer SaaS, AMIs, containers, and other software formats while supporting metering, billing, collections, and payment disbursement.
Microsoft Marketplace supports SaaS, Azure applications, containers, private offers, and customized commercial terms. These mechanisms allow ISVs to reach customers through established procurement environments rather than independently managing every transaction and billing relationship.
This development particularly supports cybersecurity, data, infrastructure, and enterprise application vendors whose customers already operate within major cloud ecosystems.
AI Applications and Agents Are Expanding the Addressable Product Base
AI is creating new software categories for ISVs, including AI agents, industry-specific copilots, data applications, and AI-enabled enterprise workflows. Microsoft positions ISV Success around building and publishing applications and agents through Microsoft Marketplace, while Google Cloud has developed an AI Agent Marketplace category for partner solutions.
The commercial opportunity extends beyond replacing legacy software, as independent vendors can add AI capabilities to established applications or develop specialized products for individual business processes.
Partner Ecosystems Are Reducing Go-to-Market Barriers
ISVs increasingly use resellers, systems integrators, cloud providers, and enterprise application ecosystems to extend distribution. Google Cloud Marketplace supports channel partners in reselling ISV products through private offers, while AWS provides marketplace channel mechanisms that allow ISVs to authorize partners to resell software.
These partnerships can provide implementation capabilities, customer relationships, and regional access for specialized software vendors.
Market Challenges
Platform Dependency Can Increase Commercial and Technical Switching Costs
Cloud marketplaces provide distribution advantages but can also increase ISV dependence on platform rules, APIs, technical standards, and commercial structures. AWS, Microsoft, Google Cloud, and Oracle each operate marketplace and partner requirements, creating ecosystem-specific integration and certification considerations.
ISVs pursuing multi-cloud distribution may need to maintain multiple integrations, commercial workflows, and support arrangements, increasing development and operational costs.
Security, Compliance and Marketplace Qualification Increase Scaling Costs
Enterprise software buyers increasingly require vendors to demonstrate security, compliance, and operational reliability. Marketplace platforms also impose publishing, validation, and technical requirements.
These requirements can increase spending on security engineering, documentation, compliance, and customer support, particularly for smaller vendors.
Market Opportunities
AI-Native Vertical Software
The expansion of AI agents creates opportunities for independent vendors to develop software around specific business processes. Google Cloud Marketplace supports discovery and deployment of partner-built AI agents, while Microsoft is developing its ISV ecosystem around AI applications and agents.
Opportunities are particularly associated with specialized workflows requiring domain-specific data, integrations, governance, and automation.
Marketplace-Native Channel Models
Cloud marketplaces allow ISVs to combine direct selling with resellers, private offers, and ecosystem-based distribution. This can create international expansion opportunities without requiring equivalent expansion of direct-sales organizations.
The model is particularly relevant to cybersecurity, data, infrastructure, and specialized enterprise applications that require implementation partners.
Market Segmentation
The Independent Software Vendors Market is segmented by Software Delivery Model, Application, Enterprise Size, and Region.
By Software Delivery Model
SaaS accounts for approximately 54% of the global ISV market in 2025. Subscription-based delivery provides recurring monetization while allowing customers to consume software without managing the full underlying infrastructure.
Cloud-Native software accounts for approximately 31% of the 2025 market and is the fastest-growing delivery model, with a projected CAGR of approximately 20.35% through 2034. Its expansion is associated with cloud architectures, containers, managed services, and AI workloads.
On-Premises & Hybrid software represents approximately 15% of the market and is projected to grow at approximately 14.00% CAGR. Hybrid deployment remains relevant for customers requiring control over sensitive data, legacy systems, or regulated workloads.
By Application
Enterprise Applications account for approximately 30% of the global market in 2025. These products support finance, human resources, customer management, operations, and other organizational processes.
Cybersecurity accounts for approximately 24% of the 2025 market and represents the fastest-growing application segment, with a projected CAGR of approximately 21.20% through 2034.
Data & Analytics accounts for approximately 19% and is projected to grow at approximately 18.60% CAGR.
Productivity & Collaboration represents approximately 15% and is projected to grow at approximately 16.80% CAGR.
Industry-Specific Software accounts for approximately 12% and is projected to grow at approximately 17.70% CAGR.
By Enterprise Size
Large enterprises account for approximately 68% of the ISV market in 2025. Their complex technology environments create demand for specialized applications integrating with cloud infrastructure, enterprise databases, security systems, and business platforms.
SMEs account for approximately 32% of the 2025 market and are projected to grow at approximately 20.10% CAGR, making them the fastest-growing enterprise-size segment.
Regional Analysis
North America
North America accounts for approximately 34% of the global ISV market in 2025 and is projected to grow at approximately 17.60% CAGR through 2034. The region benefits from a mature enterprise software ecosystem, extensive cloud adoption, and the presence of hyperscalers and platform companies.
Europe
Europe accounts for approximately 27% of the market in 2025 and is projected to grow at approximately 17.20% CAGR through 2034. Cloud procurement, enterprise modernization, data governance, security, and regulatory compliance contribute to demand for specialized software.
Asia-Pacific
Asia-Pacific accounts for approximately 23% of the global market in 2025 and is projected to grow at approximately 22.00% CAGR through 2034, making it the fastest-growing region. Growth is supported by increasing cloud adoption, enterprise digitization, and local software ecosystems.
Middle East and Africa
Middle East and Africa account for approximately 8% of the market in 2025 and are projected to grow at approximately 17.50% CAGR through 2034. Enterprise digitization, cloud adoption, cybersecurity requirements, and modernization of business applications support regional demand.
Latin America
Latin America accounts for approximately 8% of the market in 2025 and is projected to grow at approximately 17.10% CAGR through 2034. SaaS adoption and channel partnerships provide important routes for software distribution across the region.
Key Players
-
Amazon Web Services
-
Microsoft
-
Google Cloud
-
Salesforce
-
Oracle
-
SAP
-
ServiceNow
-
IBM
Competition in the Independent Software Vendors Market is increasingly shaped by distribution access, integration depth, recurring revenue models, and ecosystem positioning. AWS Marketplace provides mechanisms for ISVs to sell SaaS, AMIs, containers, and other products, while Microsoft is positioning Microsoft Marketplace and ISV Success around application development, AI agents, publishing, and enterprise sales.
Recent developments include the June 2026 general availability of AWS Marketplace Storefront, which allows ISVs and channel partners to present AWS Marketplace solutions through their own websites or applications while retaining AWS Marketplace billing infrastructure. In 2025, Microsoft expanded ISV Success around AI applications and agents, positioning the program around developing, publishing, and commercializing software through Microsoft Marketplace.
Conclusion
The Independent Software Vendors Market is projected to grow from USD 3.32 billion in 2026 to USD 12.70 billion by 2034, registering a CAGR of 18.25% during 2026–2034. Cloud marketplaces, SaaS delivery, AI applications, partner ecosystems, and specialized enterprise software are shaping market development.
SaaS currently represents the largest software delivery model with approximately 54% of the 2025 market, while Cybersecurity accounts for approximately 24% of applications and represents the fastest-growing application segment with a projected CAGR of approximately 21.20% through 2034. Large enterprises account for approximately 68% of the market, while SMEs are projected to grow at approximately 20.10% CAGR.
North America accounts for approximately 34% of the market in 2025, while Asia-Pacific is projected to grow at approximately 22.00% CAGR through 2034. Opportunities continue to emerge across AI-native vertical software, marketplace-native distribution, cybersecurity, data and analytics, and specialized enterprise applications.
Report Link:
https://reedintelligence.com/market-analysis/independent-software-vendors-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
