Tungsten Market 2026–2034: Demand Growth, Supply Dynamics & Future Opportunities
Tungsten Market Size, Share, Demand, Growth & Forecast 2026–2034
Market Overview
The Tungsten Market is experiencing steady growth due to its importance in applications requiring hardness, density, wear resistance, and high-temperature performance. Tungsten is widely used in tungsten carbide and other hardmetal products for cutting, drilling, mining, metalworking, and wear-resistant components. The market is also supported by applications across aerospace and defense, electronics and electrical, automotive, and other industrial sectors.
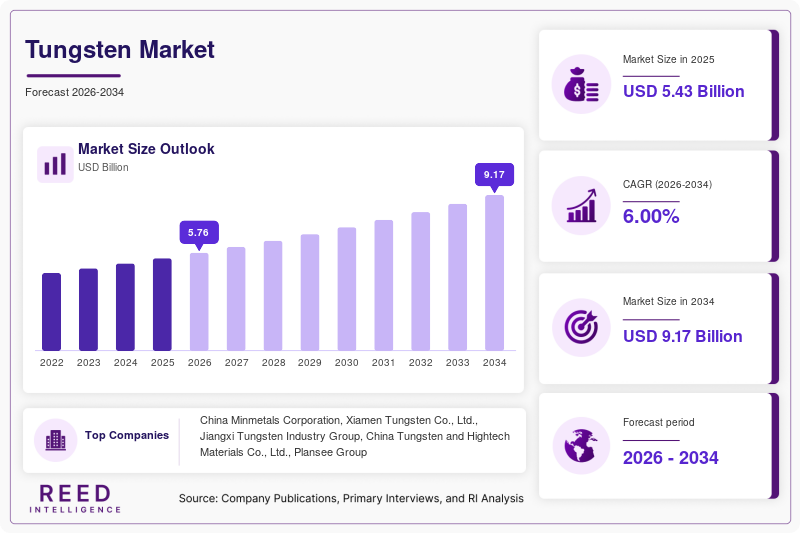
The global Tungsten Market was valued at USD 5.43 billion in 2025 and is projected to grow from USD 5.78 billion in 2026 to USD 9.17 billion by 2034. Supply concentration remains a defining feature, with China accounting for approximately 82% of global mined tungsten production in 2024. Export controls introduced by China in February 2025 covering specified tungsten-related materials and technologies have increased the importance of supply security, recycling, and alternative sources.
Request Sample Link:
https://reedintelligence.com/market-analysis/tungsten-market/request-sample
Market Size and Forecast
The global Tungsten Market is projected to grow from USD 5.78 billion in 2026 to USD 9.17 billion by 2034, registering a CAGR of 6.00% during the forecast period from 2026 to 2034. The market was valued at USD 5.43 billion in 2025.
Demand remains closely associated with industrial tooling and applications where tungsten's performance characteristics are difficult to replace. Cemented carbide represents the principal industrial pathway for tungsten consumption, particularly in cutting tools, drilling equipment, mining, construction, and metalworking.
The market is also increasingly influenced by supply-security requirements. Recycling, long-term mine offtake agreements, and alternative production outside China are becoming important mechanisms for manufacturers seeking to manage exposure to concentrated primary supply.
Market Drivers
Concentration of Tungsten Supply
China produced approximately 82% of mined tungsten globally in 2024, making supply concentration a significant factor in the market. The introduction of export controls on specified tungsten products and technologies in February 2025 has increased the importance of secure non-Chinese sources.
Manufacturers are responding through recycling, long-term offtake agreements, and efforts to diversify supply. Plansee has combined scrap collection, recycling technologies, and mine offtake agreements to strengthen its tungsten supply position.
Cemented Carbide Consumption
Tungsten carbide remains a major industrial pathway for tungsten consumption because of its hardness and wear resistance. USGS estimates that around 60% of U.S. tungsten consumption was used in cemented carbide parts in 2024, primarily for construction, metalworking, mining, and oil and gas drilling.
Strong demand for cutting tools and tungsten powder continues to connect tungsten consumption with manufacturing activity, mining equipment replacement, infrastructure investment, and industrial production.
Growing Importance of Recycling
Recycling is becoming an increasingly important supply source for tungsten. Used carbide tools contain recoverable tungsten, creating opportunities to reduce dependence on newly mined material.
Sandvik's tungsten carbide powder Bergla is made from 100% recycled tungsten raw material, while Plansee reported that recycled material accounted for 92% of its tungsten input in fiscal 2025/26. Recycling therefore supports both material recovery and raw-material security.
Market Challenges
High Supply Concentration
The concentration of primary tungsten production creates procurement and price exposure for downstream manufacturers. China produced approximately 67,000 metric tons of tungsten content in 2024 compared with approximately 81,000 metric tons of world production, according to the supplied report data.
Export controls introduced in 2025 add another layer of uncertainty for international buyers of covered tungsten materials. Manufacturers can respond through inventories, recycling, and alternative suppliers, although these approaches can increase procurement costs.
Limited Substitutability
Tungsten can be substituted in selected applications, but alternatives can involve performance or cost trade-offs. Potential substitutes for cemented tungsten carbide include molybdenum carbide, niobium carbide, titanium carbide, ceramics, cermets, and tool steels.
However, tungsten remains important in high-wear and high-temperature applications, limiting the ability of downstream users to rapidly replace it during supply disruptions.
Market Opportunities
Secondary Tungsten Supply
Closed-loop carbide recycling provides opportunities to secure part of tungsten requirements independently of newly mined supply. Sandvik has expanded customer recycling programs for used carbide tools, while Plansee combines recycling with long-term mine agreements.
The opportunity extends across tooling manufacturers, mining-equipment suppliers, and metalworking customers because used inserts, drill bits, and other carbide components provide recoverable feedstock.
New Non-Chinese Mining Projects
Supply concentration is creating opportunities for tungsten-resource development outside China. A 2025 USGS assessment of three tungsten deposits in Uzbekistan concluded that the deposits could be economically viable under 2024 market conditions. If developed, they could increase global tungsten output by approximately 2.7% and potentially make Uzbekistan the third-largest producer.
Additional diversification efforts are relevant to Australia, Europe, and other resource regions, although financing, permitting, infrastructure, and processing capabilities remain important considerations.
Market Segmentation
The Tungsten Market is segmented by Product Type, Application, and Region.
By Product Type
Tungsten Carbide
Tungsten Carbide accounted for approximately 61% of the global market in 2025. Its position reflects extensive use in cutting tools, drilling equipment, and wear-resistant components. USGS identifies cemented carbides as the largest application of tungsten, covering metalworking, mining, and construction equipment.
Demand is closely linked to machining activity, mining production, and industrial equipment replacement. Sandvik's 2025 reporting showed solid demand for tungsten powder alongside strong cutting-tool demand in aerospace and defense.
Tungsten Metal
Tungsten Metal represented approximately 17% of the market in 2025 and is projected to expand at about 7.2% CAGR through 2034. Its growth is associated with applications requiring high density, high melting temperature, and resistance to extreme operating conditions.
USGS identifies tungsten metal products in electrical, electronic, heating, welding, and specialized high-temperature applications.
Other Product Types
Tungsten Alloys are projected to expand at approximately 5.8% CAGR, while Tungsten Chemicals are projected to grow at approximately 4.9% CAGR through 2034.
By Application
Metalworking
Metalworking accounted for approximately 31% of the global market in 2025. Tungsten carbide tools are extensively used for machining hard materials, where wear resistance affects tool life and manufacturing productivity.
Aerospace & Defense
Aerospace & Defense represented approximately 15% of the market in 2025 and is expanding at about 7.5% CAGR through 2034. Tungsten's density, temperature resistance, and wear performance support specialized aerospace, defense, and high-temperature applications.
Other Applications
Mining & Construction is projected to grow at approximately 6.2% CAGR, Electronics & Electrical at 5.9%, Automotive at 5.3%, and Others at approximately 4.7% CAGR through 2034.
Regional Analysis
Asia-Pacific Tungsten Market
Asia-Pacific accounted for approximately 54% of the global market in 2025 and is projected to grow at about 6.8% CAGR through 2034. China accounted for approximately 82% of global mined tungsten production in 2024 and remains the central production and processing hub.
The region also contains major downstream manufacturing capacity across metalworking, mining equipment, electronics, and industrial tooling. China’s February 2025 export-control decision has increased the importance of supply management, inventory building, supplier diversification, and recycling.
North America Tungsten Market
North America represented approximately 18% of the global market in 2025 and is projected to grow at about 5.6% CAGR through 2034. The region has substantial downstream consumption despite limited domestic mine production.
USGS reports that tungsten has not been commercially mined in the United States since 2015. Cemented carbide applications represent a major area of U.S. consumption, while aerospace, defense, energy, oil and gas drilling, construction, and precision manufacturing contribute to regional demand.
Europe Tungsten Market
Europe accounted for approximately 17% of the global market in 2025 and is expected to grow at about 5.5% CAGR through 2034. Tungsten has strategic importance within the European raw-material framework, while the region maintains a strong downstream base in machine tools, automotive manufacturing, aerospace, medical technology, and industrial equipment.
Recycling and circular supply chains are increasingly relevant to regional supply security.
Latin America Tungsten Market
Latin America represented approximately 7% of the global market in 2025 and is projected to grow at about 5.1% CAGR through 2034. Demand is primarily connected to mining, construction, metalworking, and industrial equipment.
Brazil and Bolivia are relevant to the tungsten supply chain, with tungsten mine production reported in both countries. Growth is influenced by investment in mineral processing, infrastructure, and industrial manufacturing.
Middle East & Africa Tungsten Market
Middle East & Africa accounted for approximately 4% of the global market in 2025 and is projected to expand at about 5.0% CAGR through 2034. Demand is concentrated in mining, oil and gas, construction, and industrial equipment.
Africa also contributes to primary tungsten supply, with Rwanda among the countries reported as a tungsten producer. Greater investment in mineral-resource development could increase regional tungsten output and consumption of drilling and cutting tools.
Key Players
-
China Minmetals Corporation
-
Xiamen Tungsten Co., Ltd.
-
Jiangxi Tungsten Industry Group
-
China Tungsten and Hightech Materials Co., Ltd.
-
Plansee Group
-
Sandvik AB
-
Kennametal Inc.
-
Wolfram Bergbau und Hütten AG
Other key companies include Japan New Metals Co., Ltd. and Global Tungsten & Powders Corp.
The competitive landscape is increasingly focused on raw-material security, recycling, tungsten processing, carbide technology, tooling performance, and geographic supply reliability. Plansee combines scrap collection, tungsten recycling, and long-term mine offtake agreements, while Sandvik has expanded recycling activities for used carbide tools.
Conclusion
The Tungsten Market is projected to grow from USD 5.78 billion in 2026 to USD 9.17 billion by 2034 at a CAGR of 6.00%. Tungsten Carbide remains the largest product type with approximately 61% of the global market in 2025, while Metalworking accounted for approximately 31% of the market. Asia-Pacific represented the largest regional market with approximately 54% of global market share in 2025.
The market continues to develop around industrial tooling, aerospace and defense, mining, electronics, automotive, and other applications requiring tungsten's performance characteristics. Supply concentration, recycling, alternative sourcing, and new non-Chinese mining projects are also shaping the market's development through 2034.
The Tungsten Market presents opportunities across secondary tungsten supply, recycling, supply diversification, advanced processing, and high-performance applications as manufacturers continue to address raw-material security and industrial demand.
Report Link:
https://reedintelligence.com/market-analysis/tungsten-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
