Polyethylene Market Size, Trends, Growth and Forecast 2034
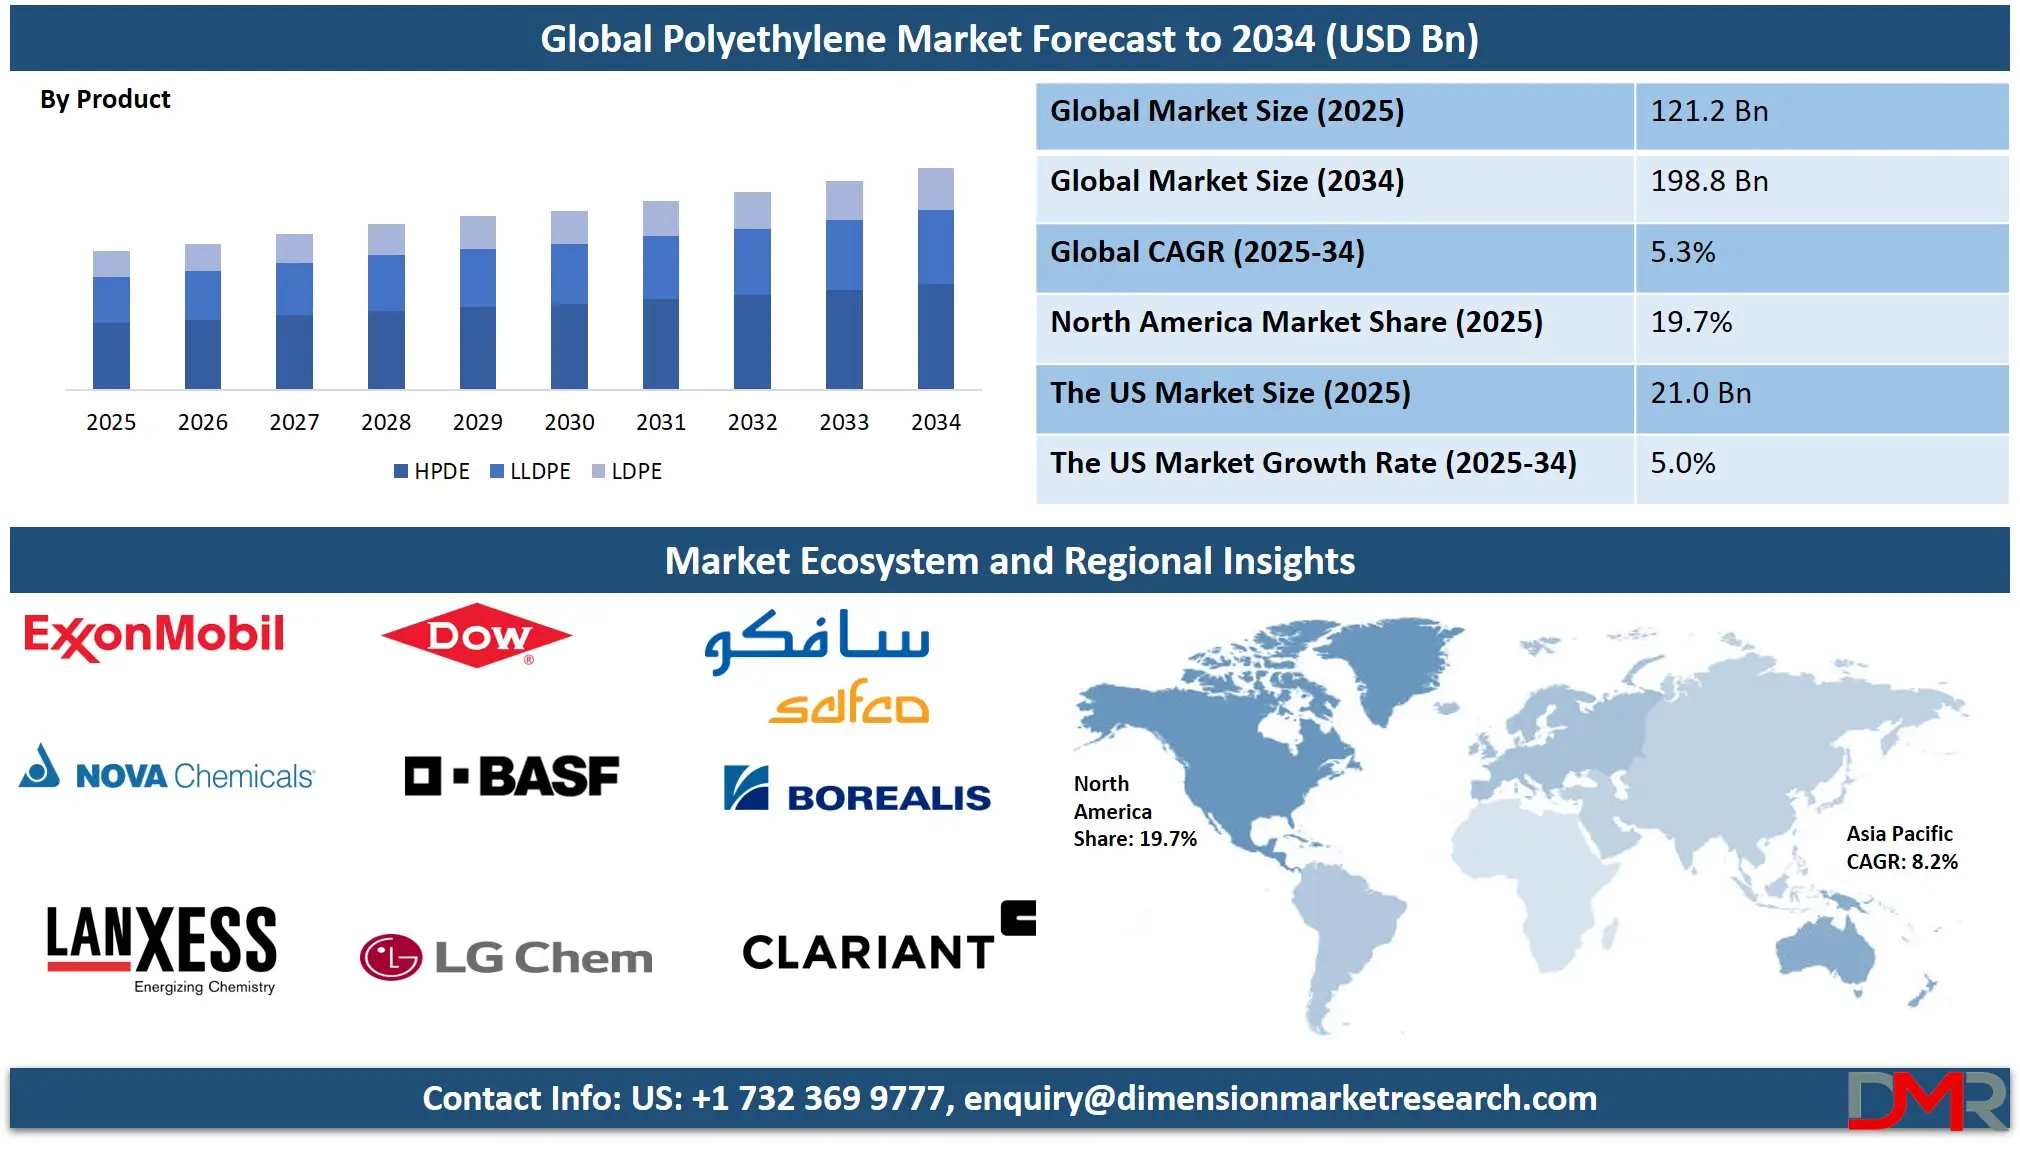
The Polyethylene Market is expanding as polyethylene remains one of the most widely used polymer materials across packaging, construction, automotive, agriculture, healthcare, and consumer applications. According to Dimension Market Research, the market is projected to reach USD 121.2 billion in 2025 and grow to USD 192.8 billion by 2034, registering a CAGR of 5.3% during the forecast period.
Polyethylene is valued for its flexibility, durability, moisture resistance, chemical resistance, lightweight structure, and versatility. Different grades, including high-density polyethylene (HDPE), low-density polyethylene (LDPE), and linear low-density polyethylene (LLDPE), allow manufacturers to develop products for applications ranging from bottles and containers to films, pipes, fittings, medical products, and industrial components.
The continued expansion of e-commerce, packaged food, consumer goods, infrastructure development, healthcare services, and automotive manufacturing is supporting demand for polyethylene-based products. At the same time, the industry is undergoing significant changes as manufacturers focus on recycling, bio-based materials, circular economy solutions, and more sustainable production processes.
Polyethylene Market Overview
Polyethylene is a thermoplastic polymer produced primarily from ethylene and is available in several grades with different physical and performance characteristics. HDPE provides strength and rigidity, LDPE offers flexibility and transparency, while LLDPE combines flexibility with improved tensile strength and puncture resistance.
These characteristics make polyethylene suitable for both rigid and flexible products. Packaging remains a major application area, while construction and infrastructure projects use polyethylene in pipes, geomembranes, insulation, and related products.
The market is also being influenced by changing sustainability requirements. Manufacturers are investing in recycled polyethylene, advanced recycling technologies, bio-based polyethylene, and improved production processes to address environmental concerns while maintaining material performance.
Key Factors Driving the Polyethylene Market
Rising Demand for Packaging
Packaging is one of the strongest demand areas for polyethylene. The material is widely used in bottles, containers, films, pouches, bags, sacks, wraps, and other packaging products because of its lightweight structure, durability, moisture resistance, and ability to protect products.
The continued expansion of e-commerce is also increasing demand for protective and flexible packaging. Food and beverage companies, personal care manufacturers, household product producers, and consumer goods companies require packaging materials that can provide product protection while remaining cost-effective.
The DMR report identifies packaging as the largest end-user segment in 2025, reflecting the importance of polyethylene in both flexible and rigid packaging applications.
Infrastructure and Construction Development
Polyethylene is increasingly used in construction and infrastructure because of its durability, corrosion resistance, flexibility, and long service life.
HDPE pipes are used for water distribution, irrigation, drainage, and other infrastructure applications. Polyethylene geomembranes are also used in applications where resistance to moisture and chemicals is important.
As cities expand and infrastructure systems are upgraded, demand for durable polymer-based materials can create additional opportunities for polyethylene manufacturers.
Growing Automotive Applications
The automotive industry is increasingly using lightweight materials to reduce vehicle weight and improve efficiency. Polyethylene can be used in selected automotive components because of its low weight, impact resistance, and durability.
The transition toward electric vehicles is also creating new material requirements. Polyethylene can be used in lightweight components, insulation-related applications, protective materials, and other automotive applications.
Expansion of Healthcare Applications
Healthcare represents another important application area for polyethylene. The material is used in medical packaging, tubing, containers, protective products, and selected medical components.
Its chemical resistance and compatibility with sterilization processes make specific polyethylene grades useful for healthcare applications. Increasing healthcare investment and demand for medical products can therefore support specialized polyethylene consumption.
Request a Free Sample Report
Businesses operating in polymer manufacturing, packaging, construction, automotive, healthcare, agriculture, and consumer products can review the research scope and methodology through the sample report.
https://dimensionmarketresearch.com/request-sample/polyethylene-market/
Polyethylene Market Trends
Shift Toward Recyclable Polyethylene
Sustainability has become one of the most important trends influencing polyethylene production and consumption. Manufacturers and packaging companies are increasingly focusing on recyclable materials and designs that support easier recovery and reuse.
Recycled polyethylene can help reduce dependence on virgin polymer feedstock while supporting circular material flows. Advanced recycling technologies are also being developed to improve the recovery of polymer materials that are difficult to process through conventional mechanical recycling.
Growth of Bio-Based Polyethylene
Bio-based polyethylene is gaining attention as manufacturers look for alternative feedstocks. Renewable sources such as sugarcane can be used to produce bio-based polyethylene while maintaining many of the properties associated with conventional polyethylene.
The development of renewable feedstock solutions creates opportunities for manufacturers seeking to reduce reliance on fossil-based raw materials.
Increasing Demand for High-Performance Grades
Industrial users are increasingly seeking polyethylene grades with improved strength, wear resistance, flexibility, durability, and temperature performance.
Specialized materials such as ultra-high-molecular-weight polyethylene and cross-linked polyethylene can serve demanding industrial, infrastructure, healthcare, and engineering applications.
This trend is encouraging manufacturers to develop higher-value polyethylene products rather than relying only on conventional commodity grades.
Greater Focus on Circular Economy Models
Circular economy strategies are changing how polyethylene products are designed, manufactured, used, collected, and recycled.
Companies are increasingly exploring closed-loop recycling, recycled-content packaging, chemical recycling, and improved waste collection systems. These initiatives can help address environmental concerns while creating additional demand for recycled polymer feedstock.
Polyethylene Market Segmentation
By Product
The polyethylene market is segmented into:
- Low-density Polyethylene (LDPE)
- High-density Polyethylene (HDPE)
- Linear Low-density Polyethylene (LLDPE)
HDPE is expected to account for the largest product share in 2025, representing approximately 47.9% of market revenue. Its durability, strength, corrosion resistance, and suitability for infrastructure applications support strong demand.
LLDPE is also expected to experience strong demand because of its flexibility, tensile strength, and suitability for films, packaging, cable insulation, and other applications.
By Application
The market is divided into:
- Bottles & Containers
- Films & Sheets
- Bags & Sacks
- Pipes & Fittings
- Others
Bottles and containers are projected to account for approximately 37.8% of market revenue in 2025. Their lightweight structure, durability, moisture resistance, and versatility make polyethylene suitable for food, beverage, personal care, household, and industrial packaging.
Films and sheets represent another major application category, particularly across flexible packaging, agriculture, industrial wrapping, and protective applications.
By End User
The market is segmented into:
- Packaging
- Construction
- Automotive
- Agriculture
- Consumer Electronics
- Others
Packaging is expected to hold the largest revenue share in 2025. Its extensive use across food, beverages, consumer goods, e-commerce, personal care, and industrial products continues to support polyethylene consumption.
Regional Outlook
Asia-Pacific
Asia-Pacific is expected to remain the leading regional market, accounting for approximately 48.5% of revenue in 2025. Demand is supported by expanding manufacturing, construction, automotive production, packaging, and consumer industries.
China represents an important contributor because of its large manufacturing base and infrastructure development. India, Japan, South Korea, Australia, and Southeast Asian markets also provide opportunities through industrial development, urbanization, packaging demand, and infrastructure investment.
North America
North America represents an important market for polyethylene across packaging, construction, automotive, healthcare, agriculture, and industrial applications.
The U.S. polyethylene market is projected to reach USD 21.0 billion in 2025, with a CAGR of 5.0% over the forecast period. Sustainable packaging, recycling initiatives, healthcare applications, electric vehicles, construction, and infrastructure development are identified as important areas of opportunity.
Europe
Europe is experiencing increased attention toward sustainable materials, recycling infrastructure, and circular economy practices. Demand for polyethylene continues across packaging, automotive, healthcare, construction, and manufacturing.
Germany has an important position because of its strong industrial and automotive sectors, while other European markets are also investing in recycling technologies and sustainable material solutions.
Latin America
Latin America offers opportunities through packaging, agriculture, infrastructure, and consumer product applications. Brazil, Mexico, Argentina, and Colombia represent important markets for polyethylene consumption.
Agricultural films, packaging materials, pipes, containers, and industrial products can contribute to regional demand.
Middle East & Africa
The Middle East and Africa provide opportunities through infrastructure development, construction, packaging, agriculture, and industrial applications. Saudi Arabia, the UAE, South Africa, Israel, and Egypt are among the markets covered in the DMR regional analysis.
Opportunities in the Polyethylene Market
Sustainable Packaging Solutions
The transition toward recyclable and environmentally conscious packaging creates opportunities for polyethylene manufacturers. Companies that can provide recyclable products while maintaining strength, barrier performance, flexibility, and cost efficiency can address changing packaging requirements.
Recycled Polyethylene
Increasing demand for recycled content is creating opportunities across the polyethylene value chain. Improvements in collection, sorting, mechanical recycling, and chemical recycling can increase the availability of recycled polymer materials.
Bio-Based Materials
Bio-based polyethylene provides another opportunity for manufacturers and brands seeking renewable feedstock options. Continued investment in bio-based production can expand the range of sustainable polyethylene solutions available to end users.
Healthcare and Medical Applications
Growing healthcare demand can support consumption of specialized polyethylene grades used in medical packaging, tubing, containers, and selected medical products.
Electric Vehicle Applications
The expansion of electric vehicle production creates opportunities for lightweight polymer materials. Polyethylene can support selected applications where weight reduction, insulation, durability, and impact resistance are important.
Challenges Facing the Polyethylene Market
Environmental Concerns
Plastic waste and pollution remain significant challenges for polyethylene producers and users. Regulations targeting single-use plastics, waste management, recycling, and plastic pollution can affect product demand and manufacturing strategies.
Companies are therefore under increasing pressure to develop recyclable products, incorporate recycled content, and improve waste recovery systems.
Raw Material Price Volatility
Polyethylene production depends heavily on hydrocarbon-based feedstocks. Changes in crude oil and natural gas prices can influence production costs and product pricing.
Energy costs, transportation expenses, supply chain disruptions, and trade restrictions can further affect operating margins and material availability.
Recycling Infrastructure Limitations
Although recycling technologies continue to improve, collection and sorting infrastructure remains uneven across markets. Contamination, mixed-material packaging, and inadequate collection systems can make recycling more difficult.
Increasing investment in waste management infrastructure and advanced recycling technologies will be important for expanding circular polyethylene production.
Competitive Landscape
The polyethylene industry includes major chemical and polymer producers competing through capacity expansion, product development, sustainability initiatives, recycling technologies, and strategic partnerships.
Prominent companies identified in the DMR report include Exxon Mobil, Dow Inc., SABIC, Borealis, NOVA Chemicals, TotalEnergies, LG Chem, Sumitomo Chemical, PetroChina Company Limited, NPC, BASF SE, Lanxess, Clariant, Arkema, and Eastman Chemical Company.
Companies are increasingly focusing on sustainable polyethylene, recycled materials, advanced grades, production efficiency, and circular economy initiatives to respond to changing customer and regulatory requirements.
Future Outlook
The polyethylene market is expected to maintain steady growth as packaging, infrastructure, automotive, healthcare, agriculture, and consumer applications continue to require versatile polymer materials.
According to Dimension Market Research, the market is projected to increase from USD 121.2 billion in 2025 to USD 192.8 billion by 2034, representing a CAGR of 5.3%.
Future market development will increasingly depend on the balance between conventional polyethylene demand and the transition toward recyclable, recycled, and bio-based alternatives.
Packaging will remain an important demand center, while infrastructure, healthcare, electric vehicles, advanced industrial materials, and sustainable packaging can create additional opportunities.
The development of efficient recycling systems, improved material design, advanced processing technologies, and renewable feedstock solutions is expected to shape the next phase of polyethylene industry development.
Frequently Asked Questions
What is the size of the Polyethylene Market?
The Polyethylene Market is projected to reach USD 121.2 billion in 2025 and USD 192.8 billion by 2034, expanding at a CAGR of 5.3%.
Which polyethylene product segment is leading?
HDPE is expected to hold the largest product share in 2025, supported by demand from construction, infrastructure, pipes, geomembranes, and other durable applications.
Which application segment has the largest share?
Bottles and containers are projected to account for approximately 37.8% of market revenue in 2025, supported by strong demand for durable and lightweight packaging.
Which region has the largest Polyethylene Market share?
Asia-Pacific is expected to hold approximately 48.5% of market revenue in 2025, supported by manufacturing, packaging, construction, automotive, and infrastructure activity.
What are the major challenges in the Polyethylene Market?
Environmental concerns, plastic waste regulations, raw material price volatility, supply chain disruptions, and limitations in recycling infrastructure are among the key challenges affecting the industry.
Conclusion
The Polyethylene Market continues to benefit from its broad application base and versatile material characteristics. Packaging remains a major source of demand, while construction, automotive, healthcare, agriculture, and industrial applications provide additional growth opportunities.
At the same time, sustainability is reshaping the industry. Recycled polyethylene, bio-based polyethylene, advanced recycling, circular economy models, and high-performance polymer grades are becoming increasingly important.
As companies and governments focus on resource efficiency and improved waste management, polyethylene manufacturers will need to balance material performance and cost with changing environmental requirements. Innovation across product design, recycling, renewable feedstocks, and manufacturing processes will remain central to the industry's development through 2034.
 Spanish
 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
