General Surgical Devices Market Growth Accelerates with Rising Global Surgical Volumes
General Surgical Devices Market Size, Share & Trends Analysis Report, 2026-2034
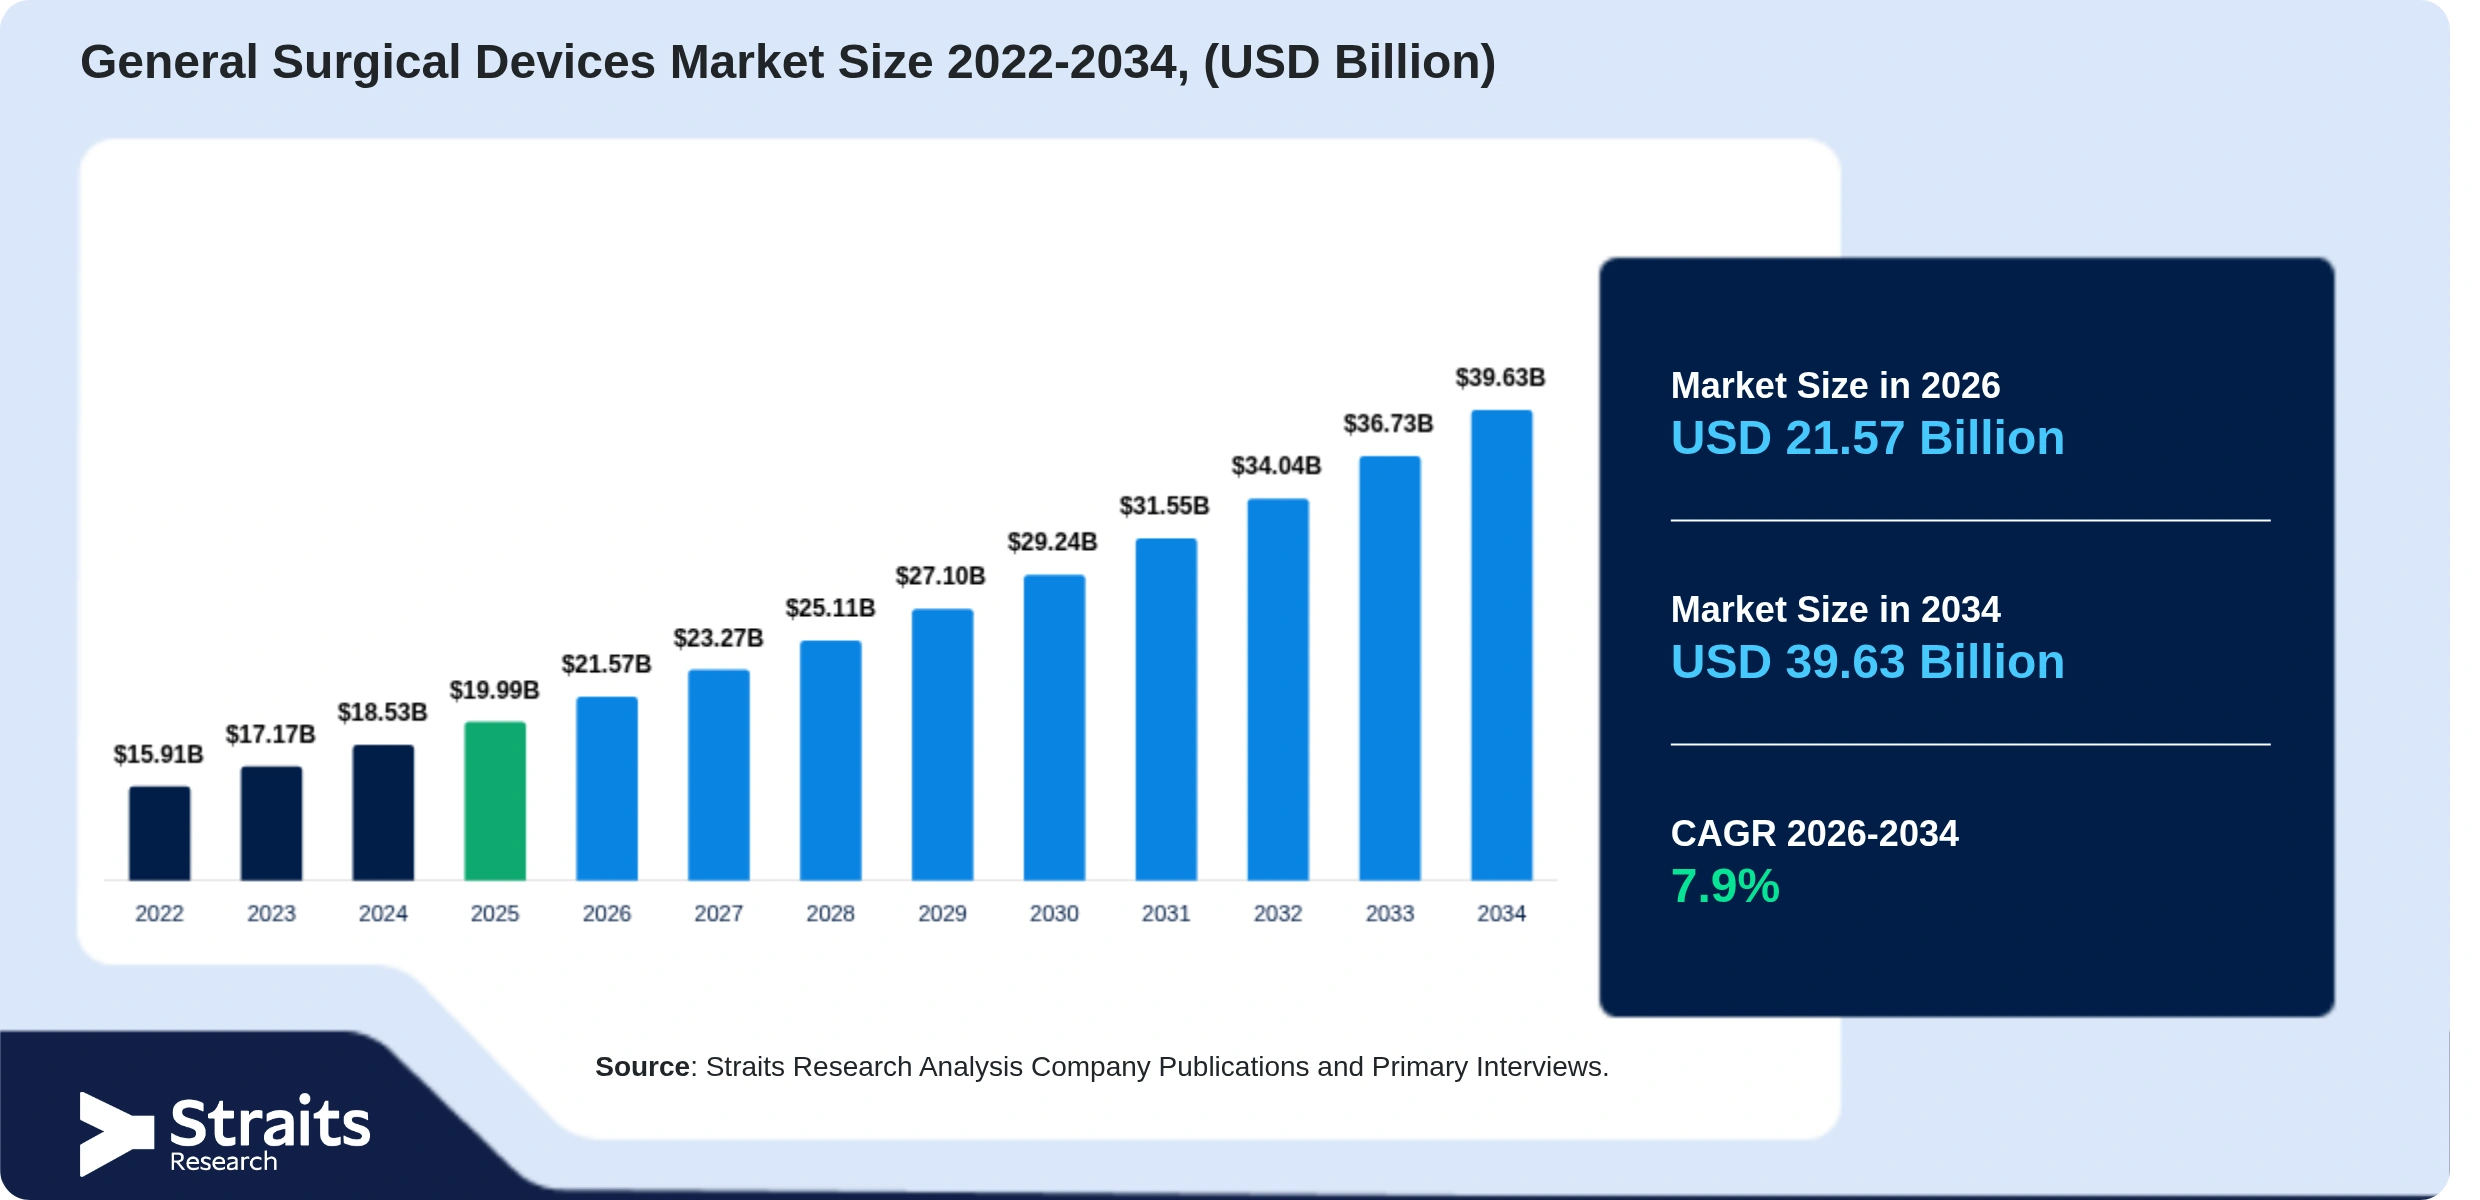
The global general surgical devices market was valued at USD 19.99 billion in 2025 and is projected to grow from USD 21.57 billion in 2026 to USD 39.63 billion by 2034, registering a CAGR of 7.9% during the forecast period from 2026 to 2034. North America dominated the general surgical devices market with a 38% market share in 2025. The market is supported by the rising volume of surgical procedures, increasing healthcare expenditure, technological advancements, and growing adoption of minimally invasive and robotic-assisted surgical technologies.
Request Sample: https://straitsresearch.com/report/general-surgical-devices-market/request-sample
Market Overview
General surgical devices are medical instruments used for common and sophisticated surgical procedures. These devices support a wide range of functions, including cutting and dissecting, grabbing and holding, clamping and occluding, exposing and retracting, suturing and stapling, viewing, and suctioning.
General surgical devices are utilized across several medical specialties, including orthopedics, neurology, obstetrics, urology, and gynecology. The increasing number of surgeries globally has strengthened demand for surgical instruments and devices.
Healthcare expenditure has increased substantially over the past few decades, supporting the need for advanced medical equipment. The growing disease burden, rising geriatric population, increasing prevalence of infectious diseases, road accidents, and growing demand for disposable surgical supplies are also contributing to market expansion.
Market Size and Forecast
The global general surgical devices market was valued at USD 19.99 billion in 2025. It is expected to reach USD 21.57 billion in 2026 and USD 39.63 billion by 2034. The market is projected to register a CAGR of 7.9% from 2026 to 2034.
Market Drivers
Increasing Number of Surgical Procedures
The growing volume of surgeries worldwide is a major factor driving demand for general surgical devices. These instruments are required for a wide range of procedures, including thoracic, abdominal, orthopedic, and other surgeries.
The rising disease burden and increasing availability of novel medical therapies are contributing to higher healthcare expenditure. Healthcare spending in countries such as India and China is also expected to increase, supporting demand for surgical devices.
Technological Advancements
Technological advancements are creating new opportunities for the general surgical devices market. Manufacturers are investing in research and development to introduce more advanced surgical instruments.
The development of medical robotics is an important technological advancement. Medical robots can provide benefits such as a 3D perspective of the operating field, reduced blood loss and transfusions, lower infection risk, faster recovery, reduced scarring, and high precision.
Growing Adoption of Minimally Invasive Procedures
Demand for minimally invasive procedures is supporting the development of advanced surgical instruments. Minimally invasive surgery instruments are expected to witness the fastest growth among the major type segments due to the rising adoption of minimally invasive cosmetic and orthopedic surgeries.
Market Challenges
Stringent Regulatory Processes
Extensive and stringent regulatory processes represent a significant challenge for medical device manufacturers. Ineffective, uncertain, and costly regulatory procedures can delay the introduction of new medical devices.
The pre-market process for devices involving discussions with the FDA regarding clinical studies for low- to moderate-risk devices before regulatory filing can take an average of 30 months. In Europe, the same process takes an average of seven months.
Limited Medical Facilities in Developing Regions
The increased risk and unavailability of medical facilities in underdeveloped regions can restrict market expansion. Although the lack of medical facilities also creates opportunities for market participants, inadequate infrastructure may slow adoption and revenue growth.
Competition and Reimbursement Concerns
The development of new minimally invasive surgery technologies and intense competition among existing general surgical device manufacturers create additional challenges. Product recalls, government initiatives to reduce healthcare costs, wholesale purchasing, and reimbursement concerns can also affect market expansion.
Market Opportunities
Advancing healthcare technology and the lack of medical facilities in developing regions are creating opportunities for companies to enter untapped markets. Global healthcare initiatives supporting sophisticated surgical techniques are expected to contribute to future market growth.
Medical robotics and computer-assisted surgical technologies represent important opportunities. The growing demand for minimally invasive procedures is encouraging manufacturers to develop devices that can reduce surgery time and complications.
Major corporations are competing through new product launches, expanded geographic presence, and educational and innovative offerings, creating further opportunities within the general surgical devices market.
Market Segmentation
By Type
The market is segmented into:
-
Disposable surgical supplies
-
Open surgery instruments
-
Energy-based and powered instruments
-
Minimally invasive surgery instruments
-
Medical robotics
-
Others
Disposable surgical supplies are expected to dominate the market due to the increasing volume of surgeries worldwide. Meanwhile, minimally invasive surgery instruments are expected to record the fastest growth due to increasing adoption of minimally invasive cosmetic and orthopedic procedures.
By Product
The market is segmented into:
-
Handheld devices
-
Laparoscopic devices
-
Others
Handheld surgical instruments account for the largest market share due to their widespread application across different surgical procedures and the increasing number of surgeries globally. However, demand for traditional manual handheld surgical tools is expected to decline during the forecast period as preferences shift toward minimally invasive procedures.
By Application
The application segments include:
-
Orthopedic
-
Cardiology
-
Wound care
-
Neurosurgery
-
Others
Orthopedic surgery dominated the market in 2021, accounting for more than 17.40% of total revenue. The segment is expected to maintain its dominance due to the increasing incidence of bone diseases and the expanding geriatric population.
The cardiology segment is expected to account for the second-largest share by 2030, supported by the rising prevalence of cardiovascular disorders.
By End-User
The market is segmented into:
-
Hospitals
-
Clinics
-
Ambulatory clinics
-
Others
Hospitals led the global industry in 2021, generating more than 58.85% of total revenue. Increasing healthcare expenditure and the growing number of hospitals and healthcare facilities are expected to support demand for general surgical devices.
Regional Analysis
North America
North America dominated the global general surgical devices market with a 38% share in 2025. The region has a well-developed healthcare sector, particularly in the U.S. and Canada, and is known for the rapid adoption of advanced healthcare technologies.
The high volume of surgical procedures and prevalence of chronic, acute, and lifestyle-related diseases such as diabetes, stroke, and obesity are supporting market growth.
Europe
Europe is estimated to be the second-largest market after Asia Pacific and is identified as the fastest-growing region in the report scope. Increasing surgical volumes and rapid adoption of advanced technologies are supporting regional growth.
More than 4.2 million cataract surgeries were conducted in European Union countries in 2014, demonstrating the substantial volume of surgical procedures in the region.
Asia Pacific
Asia Pacific is expected to register the fastest CAGR during the forecast period. Growth is attributed to the increasing number of surgeries, a large diabetic and obese population, and significant investments in healthcare by governments and private players.
The region is also experiencing increasing demand associated with road accidents and the expanding healthcare sector.
Middle East, Africa and LATAM
LAMEA is expected to experience healthy growth during the forecast period due to the growing geriatric population and increasing number of surgeries. However, limited medical facilities in Africa may slow the region's growth trajectory.
Key Players
The major companies identified in the general surgical devices market include:
-
Johnson & Johnson Services
-
Conmed Corporation
-
Dickinson and Company
-
Boston Scientific Corporation
-
Medtronic Plc
-
Cadence Inc
-
Ortho-Clinical Diagnostics Inc
-
Siemens Healthcare GmbH
Other companies identified in the competitive landscape include Hoffmann-La Roche and TransEnterix Surgical.
Recent Industry Developments
In April 2026, Medtronic plc launched next-generation general surgical instruments featuring AI-assisted energy delivery, enhanced ergonomics, and improved precision for minimally invasive procedures.
In February 2026, Johnson & Johnson MedTech (Ethicon) expanded its surgical devices portfolio with advanced stapling and tissue-sealing technologies designed to improve procedural efficiency and patient outcomes.
In October 2025, B. Braun SE expanded its surgical instrument portfolio with new minimally invasive surgical devices and enhanced operating room workflow solutions.
In June 2025, Olympus Corporation introduced upgraded laparoscopic surgical instruments with improved visualization and energy-based technologies for general surgery applications.
Conclusion
The general surgical devices market is projected to expand from USD 21.57 billion in 2026 to USD 39.63 billion by 2034, advancing at a CAGR of 7.9%. Increasing surgical volumes, rising healthcare expenditure, technological advancements, and growing adoption of minimally invasive and robotic-assisted procedures are key factors supporting market growth.
North America remains the dominant regional market, while Europe is identified as the fastest-growing region. Asia Pacific is also expected to register strong growth due to increasing surgical procedures, healthcare investments, and a large patient population.
With continued investment in advanced surgical technologies, minimally invasive procedures, medical robotics, and improved surgical instruments, the general surgical devices market is positioned for substantial growth through 2034.
Report: https://straitsresearch.com/report/general-surgical-devices-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
