Construction Plastic Market 2026: Key Trends and Growth Opportunities to Watch
Construction Plastic Market Size, Share & Trends Analysis Report
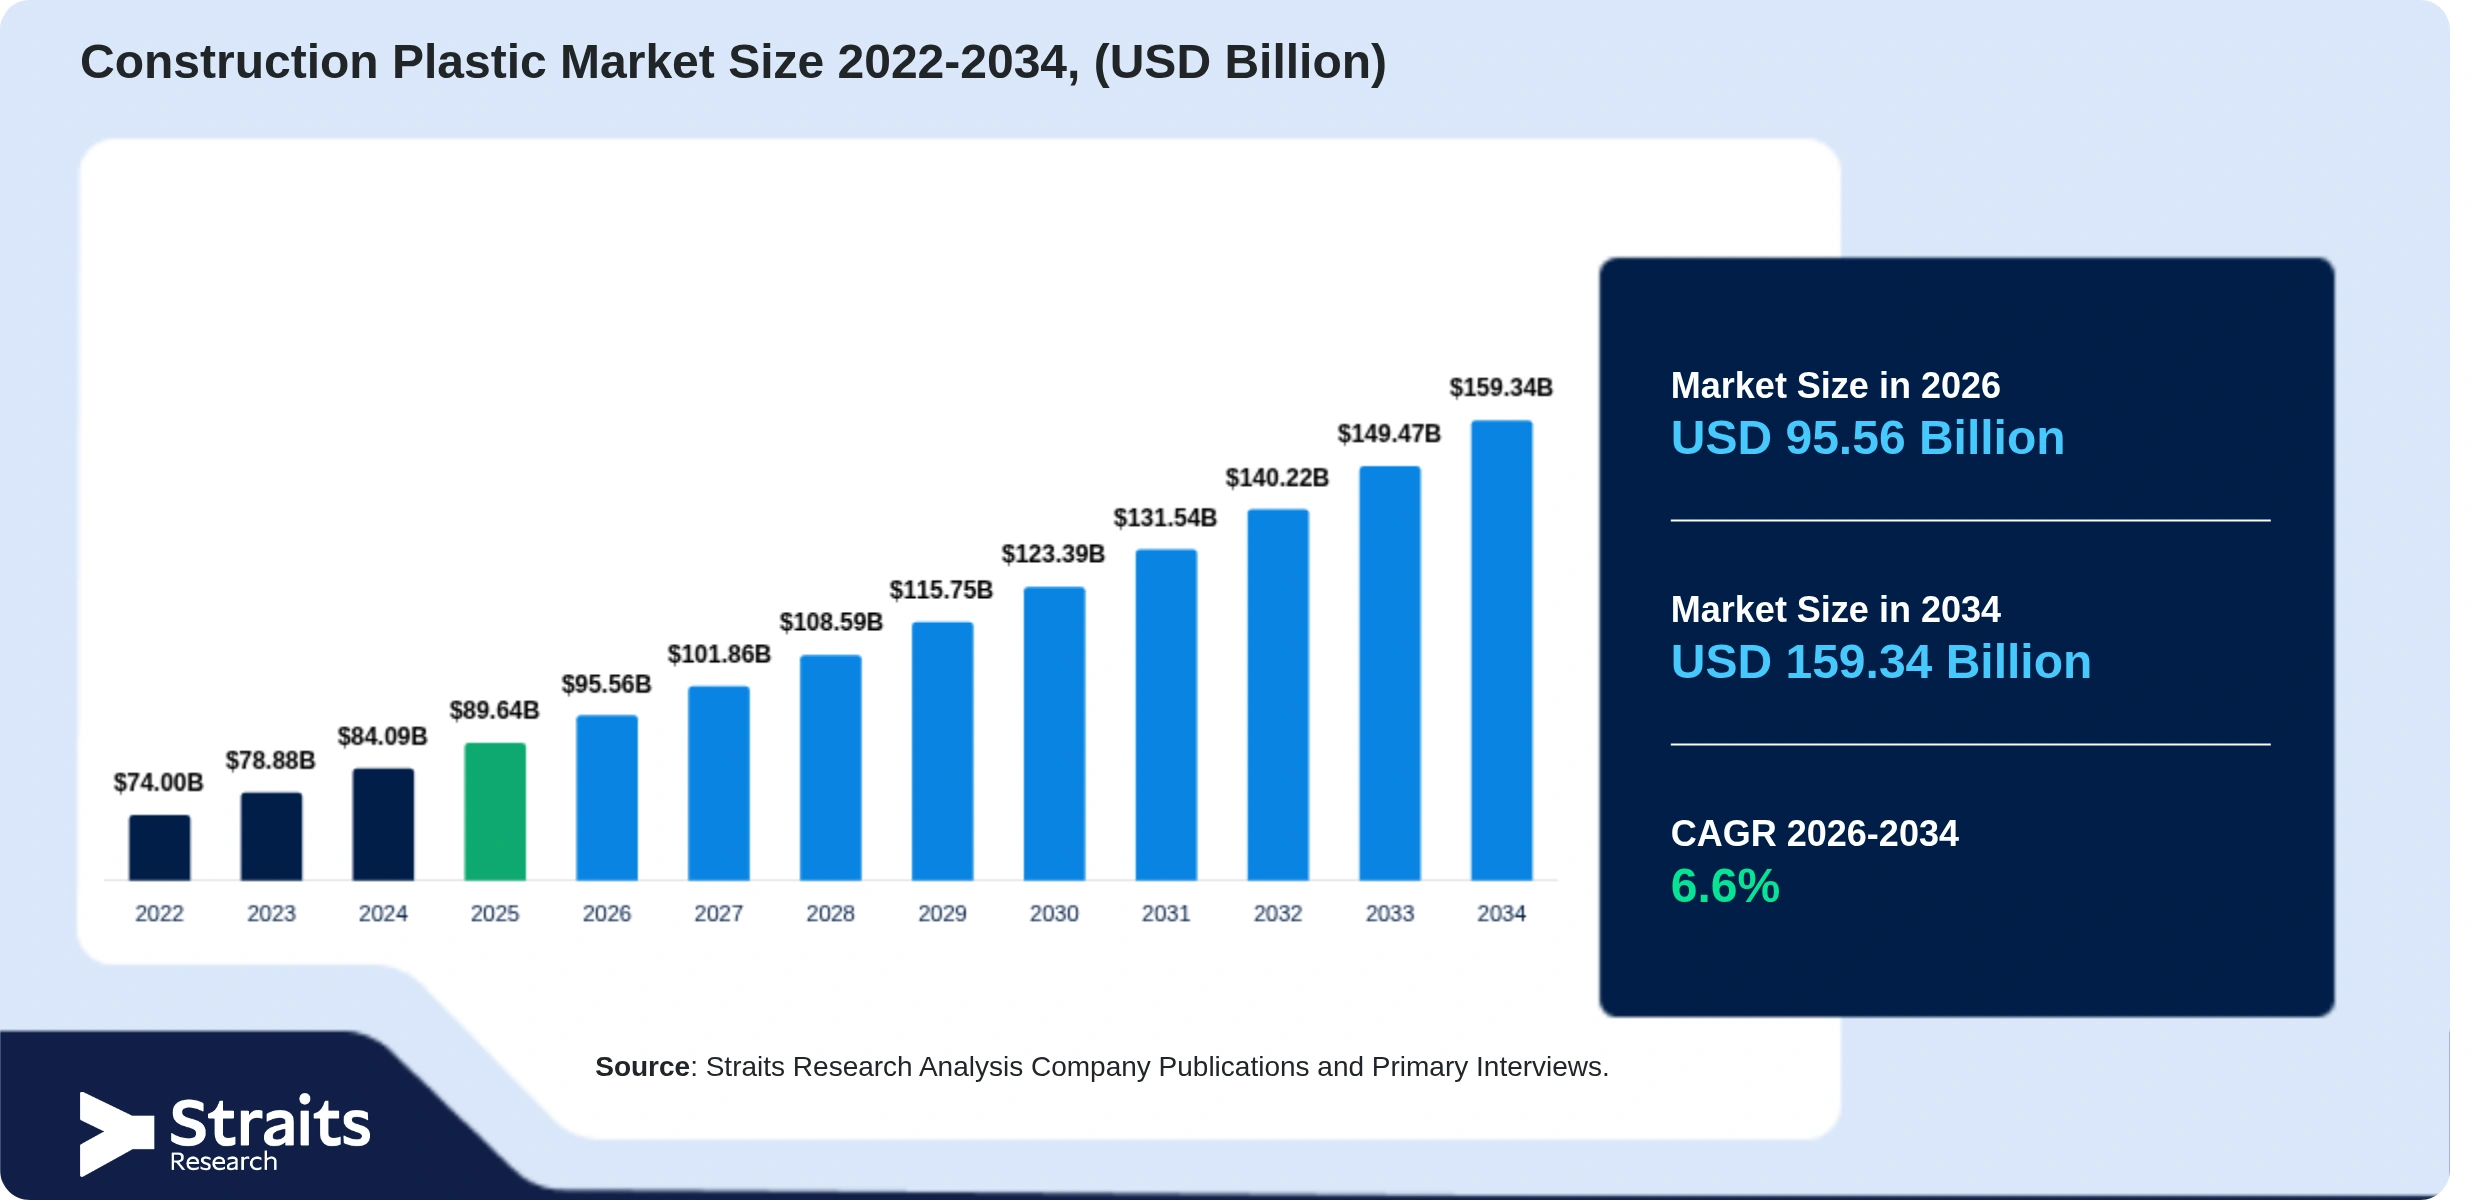
The global construction plastic market is experiencing steady expansion as construction activity, infrastructure development, and demand for durable, lightweight, corrosion-resistant, and cost-effective building materials continue to increase. The global construction plastic market size was valued at USD 89.64 billion in 2025 and is projected to grow from USD 95.56 billion in 2026 to USD 159.34 billion by 2034, registering a CAGR of 6.6% during the forecast period from 2026 to 2034. Asia Pacific dominated the construction plastic market with a 42% market share in 2025.
Request Sample: https://straitsresearch.com/report/construction-plastic-market/request-sample
Market Overview
The construction plastic market covers the production and use of plastic materials for construction applications, including pipes, insulation, flooring, roofing, windows, and structural components. Major materials include polyvinyl chloride (PVC), polyethylene, polypropylene, and other polymers.
Construction plastics provide durability, lightweight properties, corrosion resistance, and cost-effectiveness, making them suitable for residential, commercial, industrial, and infrastructure projects. The market is also evolving with greater adoption of recycled and circular construction plastics and increased demand for high-performance plastic piping systems.
The global construction plastic market is expected to reach USD 159.34 billion by 2034, compared with USD 95.56 billion in 2026, representing a CAGR of 6.6% during 2026–2034.
Market Size and Forecast
The construction plastic market was valued at USD 89.64 billion in 2025 and is projected to reach USD 95.56 billion in 2026. By 2034, the market is expected to reach USD 159.34 billion.
Market Drivers
Growing Demand for Durable and Efficient Construction Materials
Increasing construction activity and infrastructure development are supporting demand for plastic materials across pipes, insulation, flooring, roofing, and other applications. Their durability, lightweight characteristics, corrosion resistance, and cost advantages support adoption across multiple construction projects.
Expansion of Plastic Piping Systems
The transition toward high-performance plastic piping systems is another important market driver. HDPE, PEX, and other polymer pipes provide flexibility, corrosion resistance, and lower installation complexity. HDPE systems are widely used for water, wastewater, drainage, and utility applications, expanding the use of plastic piping across residential, commercial, and infrastructure projects.
Demand for Energy-Efficient Building Materials
Increasing demand for energy-efficient buildings is supporting the use of plastic-based insulation and other construction materials. The insulation segment is expected to grow at a CAGR of 7.2% from 2026 to 2034, reflecting increasing demand for improved thermal performance.
Market Challenges
Raw Material Price Volatility
Volatility in raw material prices can increase production costs for construction plastic manufacturers. Higher and unpredictable costs can raise product prices, reduce purchasing flexibility, and slow adoption among cost-sensitive construction companies.
Environmental Concerns Over Plastic Waste
Environmental concerns surrounding plastic waste and end-of-life management can limit market acceptance of conventional plastics. Manufacturers and construction companies face increasing pressure to reduce reliance on conventional plastics and improve material recovery.
Supply Chain Disruptions
Dependence on imported polymers, international shipping, and regional distribution networks can expose manufacturers to delivery delays and inventory shortages. Disruptions around the Strait of Hormuz in 2026 affected supplies of PVC and other oil-derived construction materials, contributing to project delays in several countries.
Competition from Low-Cost Imports
A fragmented supplier base and competition from low-priced imports can limit pricing power. India's plastic-pipe industry, for example, faces competition from aggressively priced imports while domestic PVC capacity remains below total demand.
Market Opportunities
Growing Adoption of Recycled Construction Plastics
The growing adoption of recycled and circular construction plastics creates opportunities for plastic recyclers, construction-material manufacturers, and building-product suppliers. Recycled PVC, rPET, and other recovered polymers are increasingly incorporated into pipes, panels, insulation, profiles, and other construction components.
This trend creates opportunities through recycled-content products, waste-to-material supply agreements, and new construction applications.
Development of High-Performance Plastic Materials
Demand for materials capable of withstanding moisture, chemicals, temperature changes, and heavy use is creating opportunities for specialized plastic manufacturers. High-performance products can support premium product lines, specialized applications, and long-term supply contracts.
Market Segmentation
By Product
Polyvinyl chloride (PVC) accounted for the largest product segment with a 32% market share in 2025. PVC is widely used in pipes, fittings, flooring, and other construction applications because of its durability, cost-effectiveness, and moisture resistance.
Polyurethanes (PU) are expected to grow at a CAGR of 7.4% during the forecast period, supported by increasing demand for insulation, sealants, and energy-efficient building materials. Thermoplastic elastomers and composite materials also contribute to construction applications through flexible, durable, and lightweight solutions.
By Application
The Pipes and Ducts segment accounted for 38% of the market in 2025. Plastic materials are extensively used in water supply, drainage, sewage, and utility systems because of their corrosion resistance, lightweight nature, and ease of installation.
The Insulation segment is expected to register a CAGR of 7.2% during 2026–2034, supported by demand for energy-efficient buildings and improved thermal performance.
By End User
Non-Residential Construction accounted for 50% of the construction plastic market in 2025. The segment benefits from extensive use of construction plastics across commercial buildings, industrial facilities, and infrastructure projects.
The segment is also expected to grow at a CAGR of 7% during the forecast period, supported by infrastructure development, commercial construction activity, and industrial expansion.
Regional Analysis
Asia Pacific
Asia Pacific accounted for the largest regional share of 42% in 2025. Rapid urbanization, infrastructure development, increasing construction activity, and rising demand for lightweight, durable, and cost-effective plastic materials are supporting regional growth.
China is benefiting from plans to build and upgrade around 770,000 km of urban underground pipelines during 2026–2030, while RMB 160 billion is earmarked for pipeline upgrades. Japan is gaining momentum from infrastructure renewal and construction investment, while South Korea is supported by infrastructure modernization, urban redevelopment, and energy-efficient building activity.
India is also expected to benefit from ₹16.72 lakh crore of asset-monetization potential under NMP 2.0 during FY2026–FY2030, including ₹5.8 lakh crore of expected private-sector investment.
North America
North America is the fastest-growing regional market, with a projected CAGR of 7.8% during 2026–2034. Growth is supported by infrastructure modernization, construction and renovation activity, demand for energy-efficient buildings, and increased use of lightweight and durable plastic materials.
Canada is benefiting from the C$51 billion Build Communities Strong Fund over 10 years starting in 2026–27, including C$17.2 billion for housing-enabling infrastructure. Build Canada Homes also has an initial C$13 billion five-year investment to accelerate housing construction.
Europe
Europe accounted for 22% of the regional market in 2025. Building renovation, infrastructure modernization, and demand for energy-efficient and sustainable construction materials are supporting market expansion.
The U.K. market is supported by a £718 billion infrastructure pipeline and £39 billion in affordable housing commitments from 2026–27 to 2035–36. Germany is benefiting from a €500 billion infrastructure and climate-neutrality special fund available through 2045. France is also creating opportunities through low-carbon investment and residential renovation initiatives.
Key Players
The construction plastic market is moderately fragmented, with participation from global polymer manufacturers, diversified chemical companies, specialized plastic-product manufacturers, regional suppliers, and niche producers.
The leading players include:
-
DowDuPont (US)
-
BASF SE (Germany)
-
Asahi Kasei Corporation (Japan)
-
LyondellBasell Industries Holdings B.V. (Netherlands)
-
Borealis AG (Austria)
-
Solvay S.A. (Belgium)
-
Saudi Basic Industries Corporation (SABIC) (Saudi Arabia)
-
Berry Plastics Corporation (US)
The five leading companies—DowDuPont, BASF SE, Asahi Kasei Corporation, LyondellBasell Industries Holdings B.V., and Borealis AG—collectively account for approximately 38% of the global construction plastic market share.
Competition is based on product quality, material performance, production capacity, distribution networks, supply consistency, technological capabilities, sustainability initiatives, pricing, customized products, and recycled or sustainable plastic solutions.
Recent Industry Developments
In April 2026, POLYVANTIS expanded its high-performance thermoplastics portfolio in India by introducing PLEXIGLAS® PMMA solutions for building and construction applications.
In April 2026, DCM Shriram and Teknor Apex established a joint venture under the PolyTek brand to strengthen advanced polymer compound capabilities.
In January 2026, ALBIS established a joint venture with Sukhesh Group in India to expand engineering plastics distribution capabilities.
In January 2026, Mount Roofing and Structures expanded its manufacturing capabilities with an automated sandwich panel production line and a new pre-engineered building manufacturing facility.
Conclusion
The global construction plastic market is projected to expand from USD 95.56 billion in 2026 to USD 159.34 billion by 2034, registering a CAGR of 6.6%. Growth is being supported by construction and infrastructure development, increasing use of plastic piping, demand for energy-efficient building materials, and the advantages of lightweight, durable, corrosion-resistant, and cost-effective plastic solutions.
Asia Pacific remains the dominant regional market, accounting for 42% of the market in 2025, while North America is projected to be the fastest-growing region with a CAGR of 7.8%. PVC remains the leading product segment, Pipes and Ducts is the largest application segment, and Non-Residential Construction represents the leading end-user segment.
The growing adoption of recycled construction plastics and high-performance materials also creates opportunities for manufacturers and suppliers to develop sustainable and specialized solutions.
With continued infrastructure investment, construction activity, renovation demand, and adoption of advanced plastic materials, the construction plastic market is positioned for sustained growth through 2034.
Report: https://straitsresearch.com/report/construction-plastic-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Greek
