Automotive Crankshaft Market 2034: Key Growth Opportunities Across Passenger and Commercial Vehicles
Automotive Crankshaft Market Size, Share & Growth Analysis 2026-2034
Market Overview
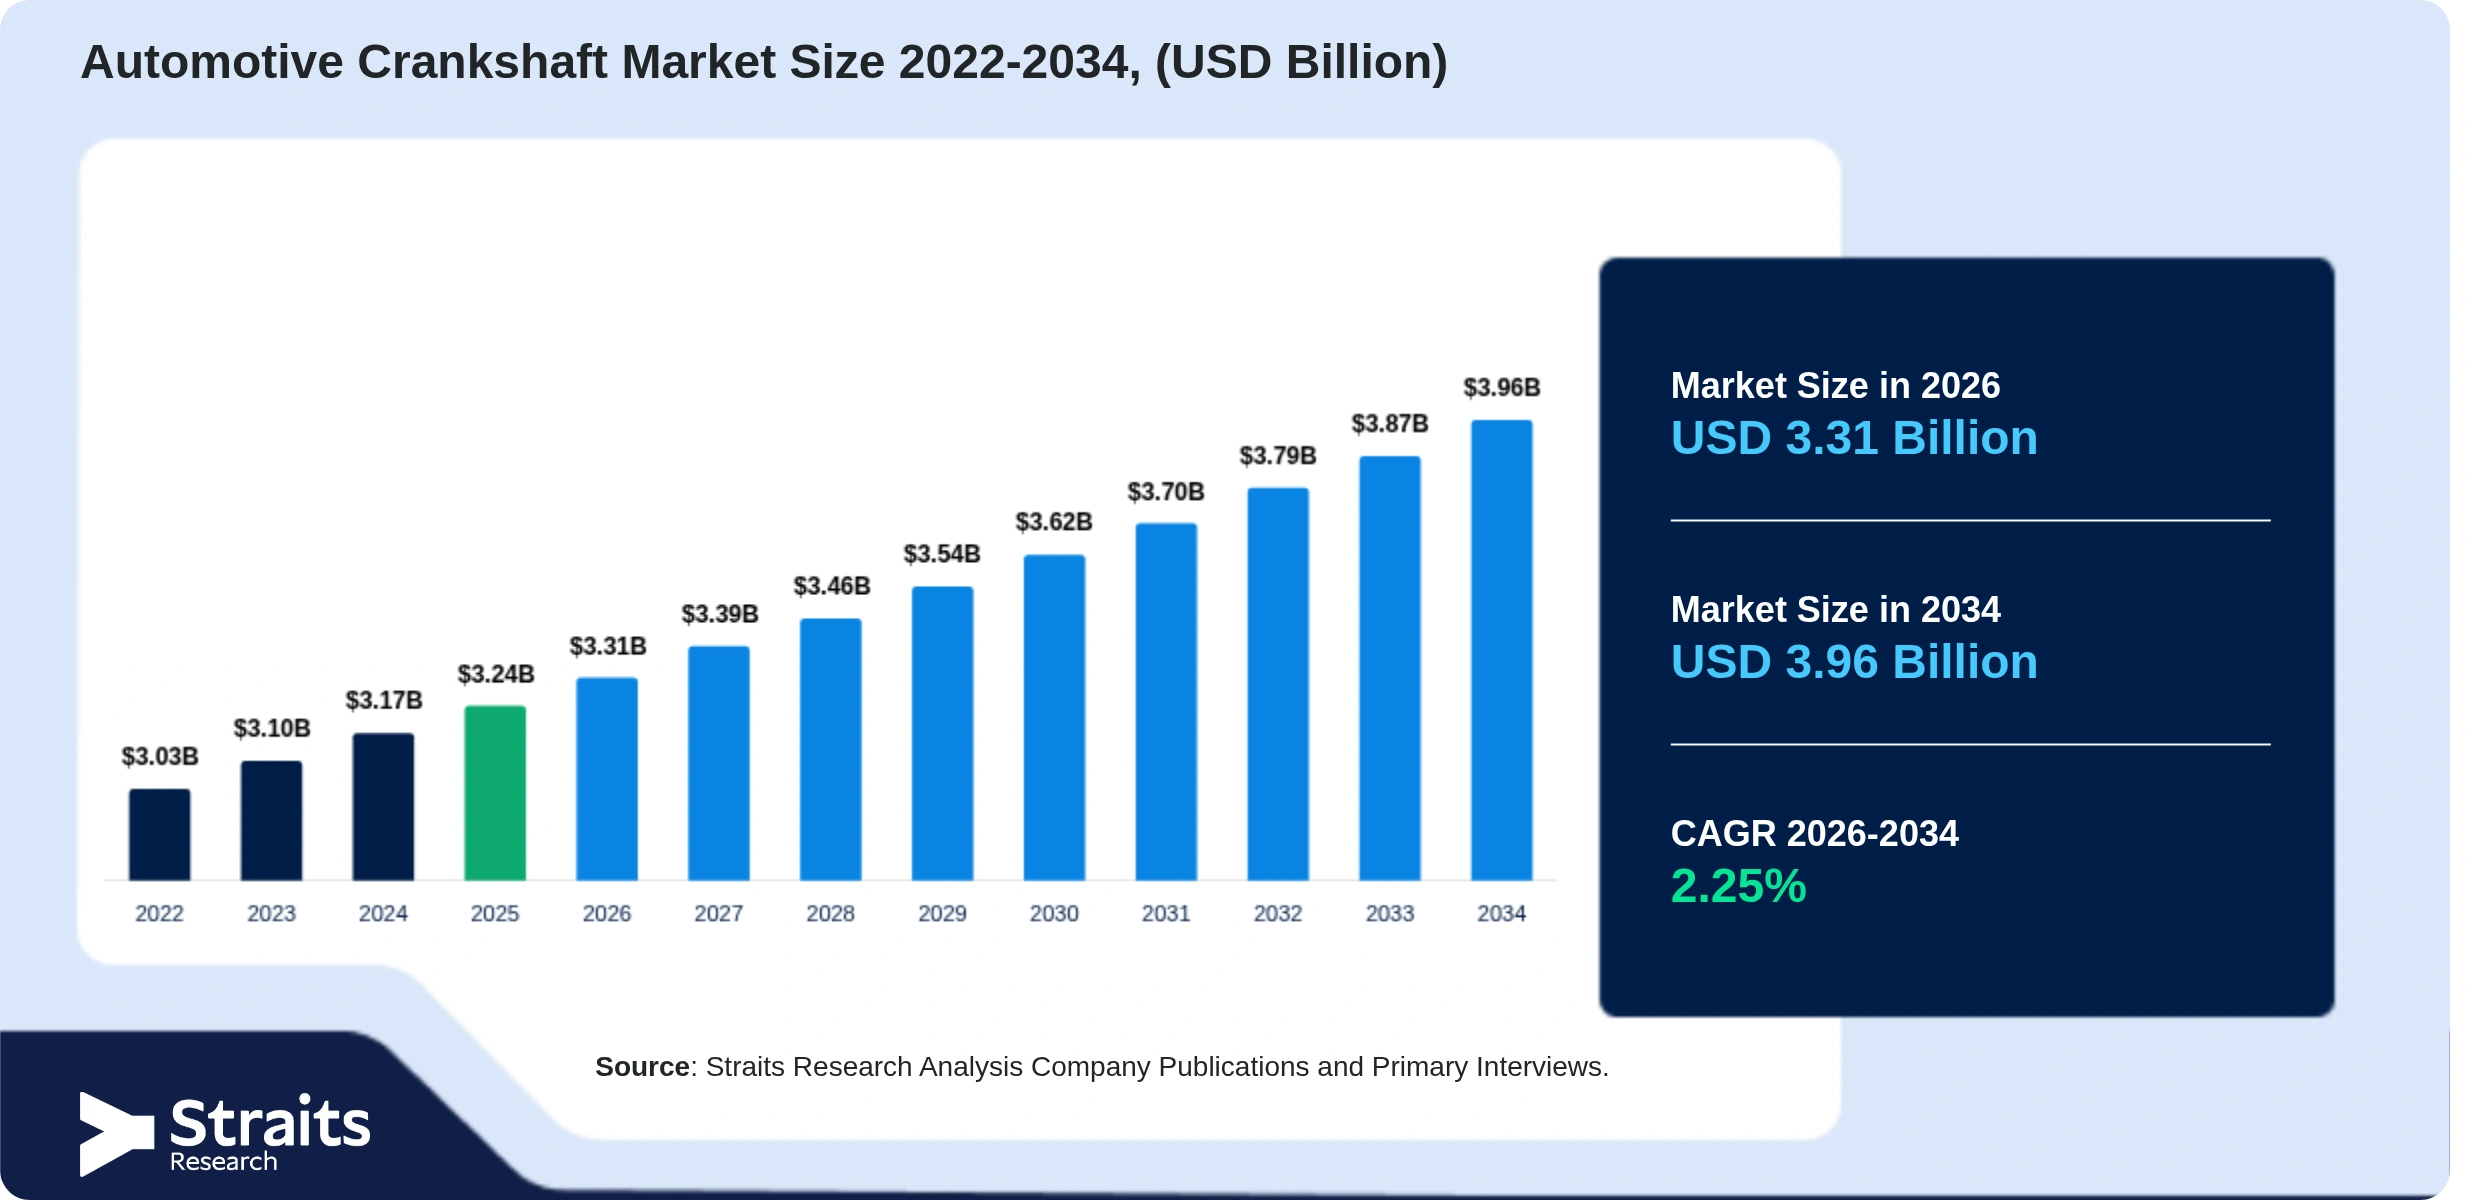
The global automotive crankshaft market was valued at USD 3.24 billion in 2025 and is projected to grow from USD 3.31 billion in 2026 to USD 3.96 billion by 2034, registering a CAGR of 2.25% during the forecast period from 2026 to 2034. Asia Pacific dominated the automotive crankshaft market with a 43.2% share in 2025, while Europe is projected to be the fastest-growing regional market with a CAGR of 5.7% during the forecast period.
An automotive crankshaft is a critical engine component that converts the reciprocating motion of pistons into rotational motion. Crankshafts are generally manufactured using steel or cast iron through forging, casting, or machining processes. The automotive crankshaft market serves passenger vehicles, commercial vehicles, SUVs, MUVs, and other automotive applications.
Growth in the market is supported by rising vehicle production, increasing demand for fuel-efficient and high-performance engines, continued development of hybrid powertrains, and advancements in precision forging and machining technologies.
Request Sample: https://straitsresearch.com/report/automotive-crankshaft-market/request-sample
Market Size and Forecast
The automotive crankshaft market is expected to maintain steady growth through 2034. The market was valued at USD 3.24 billion in 2025 and is forecast to reach USD 3.31 billion in 2026. By 2034, the market is projected to reach USD 3.96 billion, expanding at a CAGR of 2.25% between 2026 and 2034.
Asia Pacific held the largest regional share at 43.2% in 2025, supported by strong automotive manufacturing activity, rising vehicle production, demand for passenger and commercial vehicles, and increasing investment in automotive component manufacturing.
Europe is expected to register the fastest growth during the forecast period, with a projected CAGR of 5.7%. The region's automotive industry continues to focus on advanced engine technologies, lightweight components, and precision-engineered automotive systems.
Market Drivers
Rising Vehicle Production and Demand for High-Performance Engines
Increasing global vehicle production and growing demand for fuel-efficient and high-performance engines are key factors supporting automotive crankshaft market growth. Crankshafts remain essential components in internal combustion engine vehicles, hybrid vehicles, passenger cars, commercial vehicles, and heavy-duty trucks.
Automotive manufacturers are increasingly adopting lightweight forged steel and advanced alloy crankshafts to improve engine efficiency, durability, and fuel economy. Replacement demand from the automotive aftermarket also contributes to market expansion across developed and emerging economies.
Higher Engine Output Requirements
Higher engine output requirements are increasing demand for crankshafts with greater strength and durability. Turbocharged and high-torque engines place additional mechanical stress on crankshaft components.
Heavy-duty diesel engines used in pickup trucks and commercial vehicles require reinforced crankshafts capable of managing high torque under continuous operating conditions. This trend is increasing demand for stronger crankshaft designs and supporting procurement from engine and vehicle manufacturers.
Growth of Automotive Component Localization
The expansion of automotive component localization is increasing domestic crankshaft production capacity. Automotive suppliers are establishing or expanding manufacturing and machining operations closer to vehicle and engine assembly facilities.
Local production can strengthen supply capacity and procurement relationships between crankshaft suppliers, engine manufacturers, and automotive OEMs.
Market Challenges
Rising Electric Vehicle Adoption
The growing adoption of battery electric vehicles represents a significant challenge for the automotive crankshaft market because fully electric vehicles do not require conventional crankshafts.
As vehicle electrification increases, demand for traditional internal combustion engine components is expected to gradually decline. This creates long-term pressure on manufacturers that primarily depend on conventional gasoline and diesel engine platforms.
Complex Machining and Forging Processes
Crankshaft production requires specialized equipment, precision manufacturing, multiple production stages, and stringent quality requirements. Complex forging and machining processes can increase production costs and limit manufacturing efficiency.
Manufacturers must also maintain high levels of dimensional accuracy, durability, and consistency, increasing the importance of advanced production and quality-control systems.
Fluctuating Raw Material Costs
Fluctuations in steel and alloy prices can increase manufacturing costs and place pressure on supplier margins. The automotive crankshaft market also faces supply-chain disruptions affecting manufacturers that rely on internationally distributed steel sourcing, forging, machining, heat treatment, and vehicle assembly operations.
Market Opportunities
Growing Hybrid Vehicle Production
The increasing production of hybrid electric vehicles presents an important opportunity for crankshaft manufacturers. Unlike fully electric vehicles, hybrid powertrains continue to use internal combustion engines, sustaining demand for high-strength and precision-engineered crankshafts.
Investment in advanced engine designs for hybrid vehicles is supporting demand for crankshafts capable of delivering durability, reduced vibration, and improved fuel efficiency.
Lightweight Crankshaft Materials
The development of lightweight and high-strength crankshaft materials creates opportunities for automotive OEMs and component manufacturers. Lightweight crankshafts can help reduce engine weight and improve vehicle efficiency.
Material suppliers offering suitable high-strength solutions can benefit from automotive contracts, while manufacturers can develop premium crankshaft products for passenger vehicles and commercial applications where efficiency and performance are important.
Advanced Manufacturing Technologies
Precision forging, CNC machining, automated manufacturing, and advanced quality-control technologies provide opportunities to improve crankshaft performance and manufacturing efficiency.
Growing investment in advanced manufacturing technologies, particularly across Asia Pacific and Latin America, can support long-term opportunities for crankshaft manufacturers.
Market Segmentation
By Vehicle Type
The passenger vehicles segment accounted for the largest share of the automotive crankshaft market at 27.6% in 2025. The segment benefits from the large global passenger vehicle population and continued demand for fuel-efficient and high-performance engines.
Heavy commercial vehicles continue to generate demand for durable crankshafts because of their use in long-haul transportation and heavy-duty applications. Light commercial vehicles also contribute to demand, while SUVs represent an important growth segment.
The SUV segment is projected to grow at a CAGR of 5.4% during the forecast period, supported by continued consumer preference for sport utility vehicles and demand for higher-performance powertrains. MUVs and other vehicle categories continue to contribute through family transportation, commercial applications, and specialized automotive uses.
By Crankshaft Type
The cross plane segment accounted for 63.3% of the automotive crankshaft market in 2025. Cross plane crankshafts are widely used in applications requiring smooth power delivery and balanced engine operation.
The segment is projected to grow at a CAGR of 5% during 2026-2034. Flat plane crankshafts continue to serve specialized applications requiring lightweight rotating assemblies and high-revving performance, particularly in performance-oriented vehicles.
By Material
The forged iron/steel segment dominated the market with a 58.6% share in 2025. Its leading position is supported by high strength, durability, fatigue resistance, and suitability for demanding engine applications.
The segment is expected to grow at a CAGR of 5.2% during the forecast period. Cast iron/steel remains widely used in cost-sensitive applications, while other materials support specialized performance and manufacturing requirements.
Regional Analysis
Asia Pacific
Asia Pacific dominated the automotive crankshaft market with a 43.2% share in 2025, representing a market value of USD 1.4 billion. The region benefits from strong automotive manufacturing activity, rising vehicle production, demand for passenger and commercial vehicles, and increasing investments in automotive component manufacturing.
China accounted for the largest share of the Asia Pacific market in 2025. Its position is supported by a large automotive manufacturing base, increasing production of passenger and commercial vehicles, expanding automotive component exports, and investment in advanced manufacturing technologies.
Japan continues to benefit from its established automotive industry, precision-engineered component capabilities, technological innovation, and focus on high-performance and fuel-efficient vehicles. India's expanding automotive manufacturing activity also provides opportunities for crankshaft suppliers.
Europe
Europe accounted for 25.6% of the global automotive crankshaft market in 2025, reaching USD 0.83 billion. The region is projected to expand at a CAGR of 5.7% during 2026-2034.
Market growth is supported by leading automobile manufacturers, demand for premium and performance vehicles, advanced engine technologies, and the adoption of lightweight and high-strength automotive components.
Germany represents the largest market in Europe, supported by its strong automotive manufacturing sector, premium vehicle production, advanced engine technologies, and demand for precision-engineered crankshafts.
North America
North America accounted for 21.4% of the global automotive crankshaft market in 2025, with a market value of USD 0.69 billion. The region benefits from demand for passenger vehicles, pickup trucks, and commercial vehicles, alongside investments in automotive manufacturing and advanced engine components.
The United States represented the largest share of the North American market in 2025. Growth is supported by vehicle production, aftermarket demand, advanced manufacturing technologies, and the presence of major automotive manufacturers and suppliers.
Middle East & Africa
The Middle East & Africa market represented 4.0% of the global automotive crankshaft market in 2025, totaling USD 0.13 billion.
Rising vehicle ownership, automotive assembly and manufacturing investments, aftermarket demand, and infrastructure development are supporting regional growth. The UAE remains an important market due to demand for passenger and luxury vehicles, automotive aftermarket services, and high-quality components.
Africa is witnessing gradual market growth supported by increasing vehicle ownership, automotive assembly operations, transport infrastructure investment, and demand for replacement engine components.
Key Players
The automotive crankshaft market is moderately fragmented and includes global automotive component manufacturers, specialized crankshaft producers, forged and machined component suppliers, and regional manufacturers.
The leading players include:
-
Bharat Forge Ltd
-
Bryant Racing Inc.
-
Tianrun Crankshaft Co. Ltd.
-
NSI Crankshaft
-
ThyssenKrupp Crankshaft Company LLC
-
Arrow Precision
-
Maschinenfabrik ALFING KESSLER GmbH
-
Ciguenales Sanz SL
Mahindra CIE Automotive Ltd. is also identified among the key and emerging players in the market.
Market participants compete on manufacturing scale, dimensional precision, material strength, durability, production consistency, advanced forging and machining capabilities, cost efficiency, customized designs, lightweight materials, and relationships with automotive manufacturers.
Conclusion
The global automotive crankshaft market is projected to grow from USD 3.31 billion in 2026 to USD 3.96 billion by 2034, registering a CAGR of 2.25%. Rising vehicle production, demand for high-performance engines, increasing hybrid vehicle production, automotive component localization, and advancements in precision manufacturing are supporting market growth.
At the same time, increasing electric vehicle adoption, fluctuating raw material costs, complex manufacturing processes, supply-chain disruptions, and the gradual shift away from conventional internal combustion engines remain important challenges.
Asia Pacific is expected to retain its leading position, while Europe is projected to be the fastest-growing regional market with a CAGR of 5.7%. Passenger vehicles remain the leading vehicle-type segment, cross plane crankshafts represent the largest crankshaft-type segment, and forged iron/steel remains the leading material segment.
With continued investment in lightweight materials, advanced forging and machining technologies, hybrid powertrains, and high-strength crankshaft designs, manufacturers have opportunities to strengthen their position across passenger vehicle, commercial vehicle, and specialized engine applications through 2034.
Report: https://straitsresearch.com/report/automotive-crankshaft-market

 English
 Arabic
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
