Asia Pacific Leads the Snack Food Market: Regional Trends and Growth Opportunities
Snack Food Market Size, Share, Trends, and Forecast 2026–2034
Market Overview
The global snack food market is experiencing steady growth, driven by changing consumer lifestyles, increasing demand for convenient food options, and rising interest in healthier and functional snacks. The industry includes ready-to-eat products consumed between regular meals, such as chips, nuts, biscuits, popcorn, snack bars, and other savory and sweet snacks. Manufacturers are expanding their product portfolios to address evolving consumer preferences for convenience, nutritional value, innovative flavors, and diverse snacking experiences.
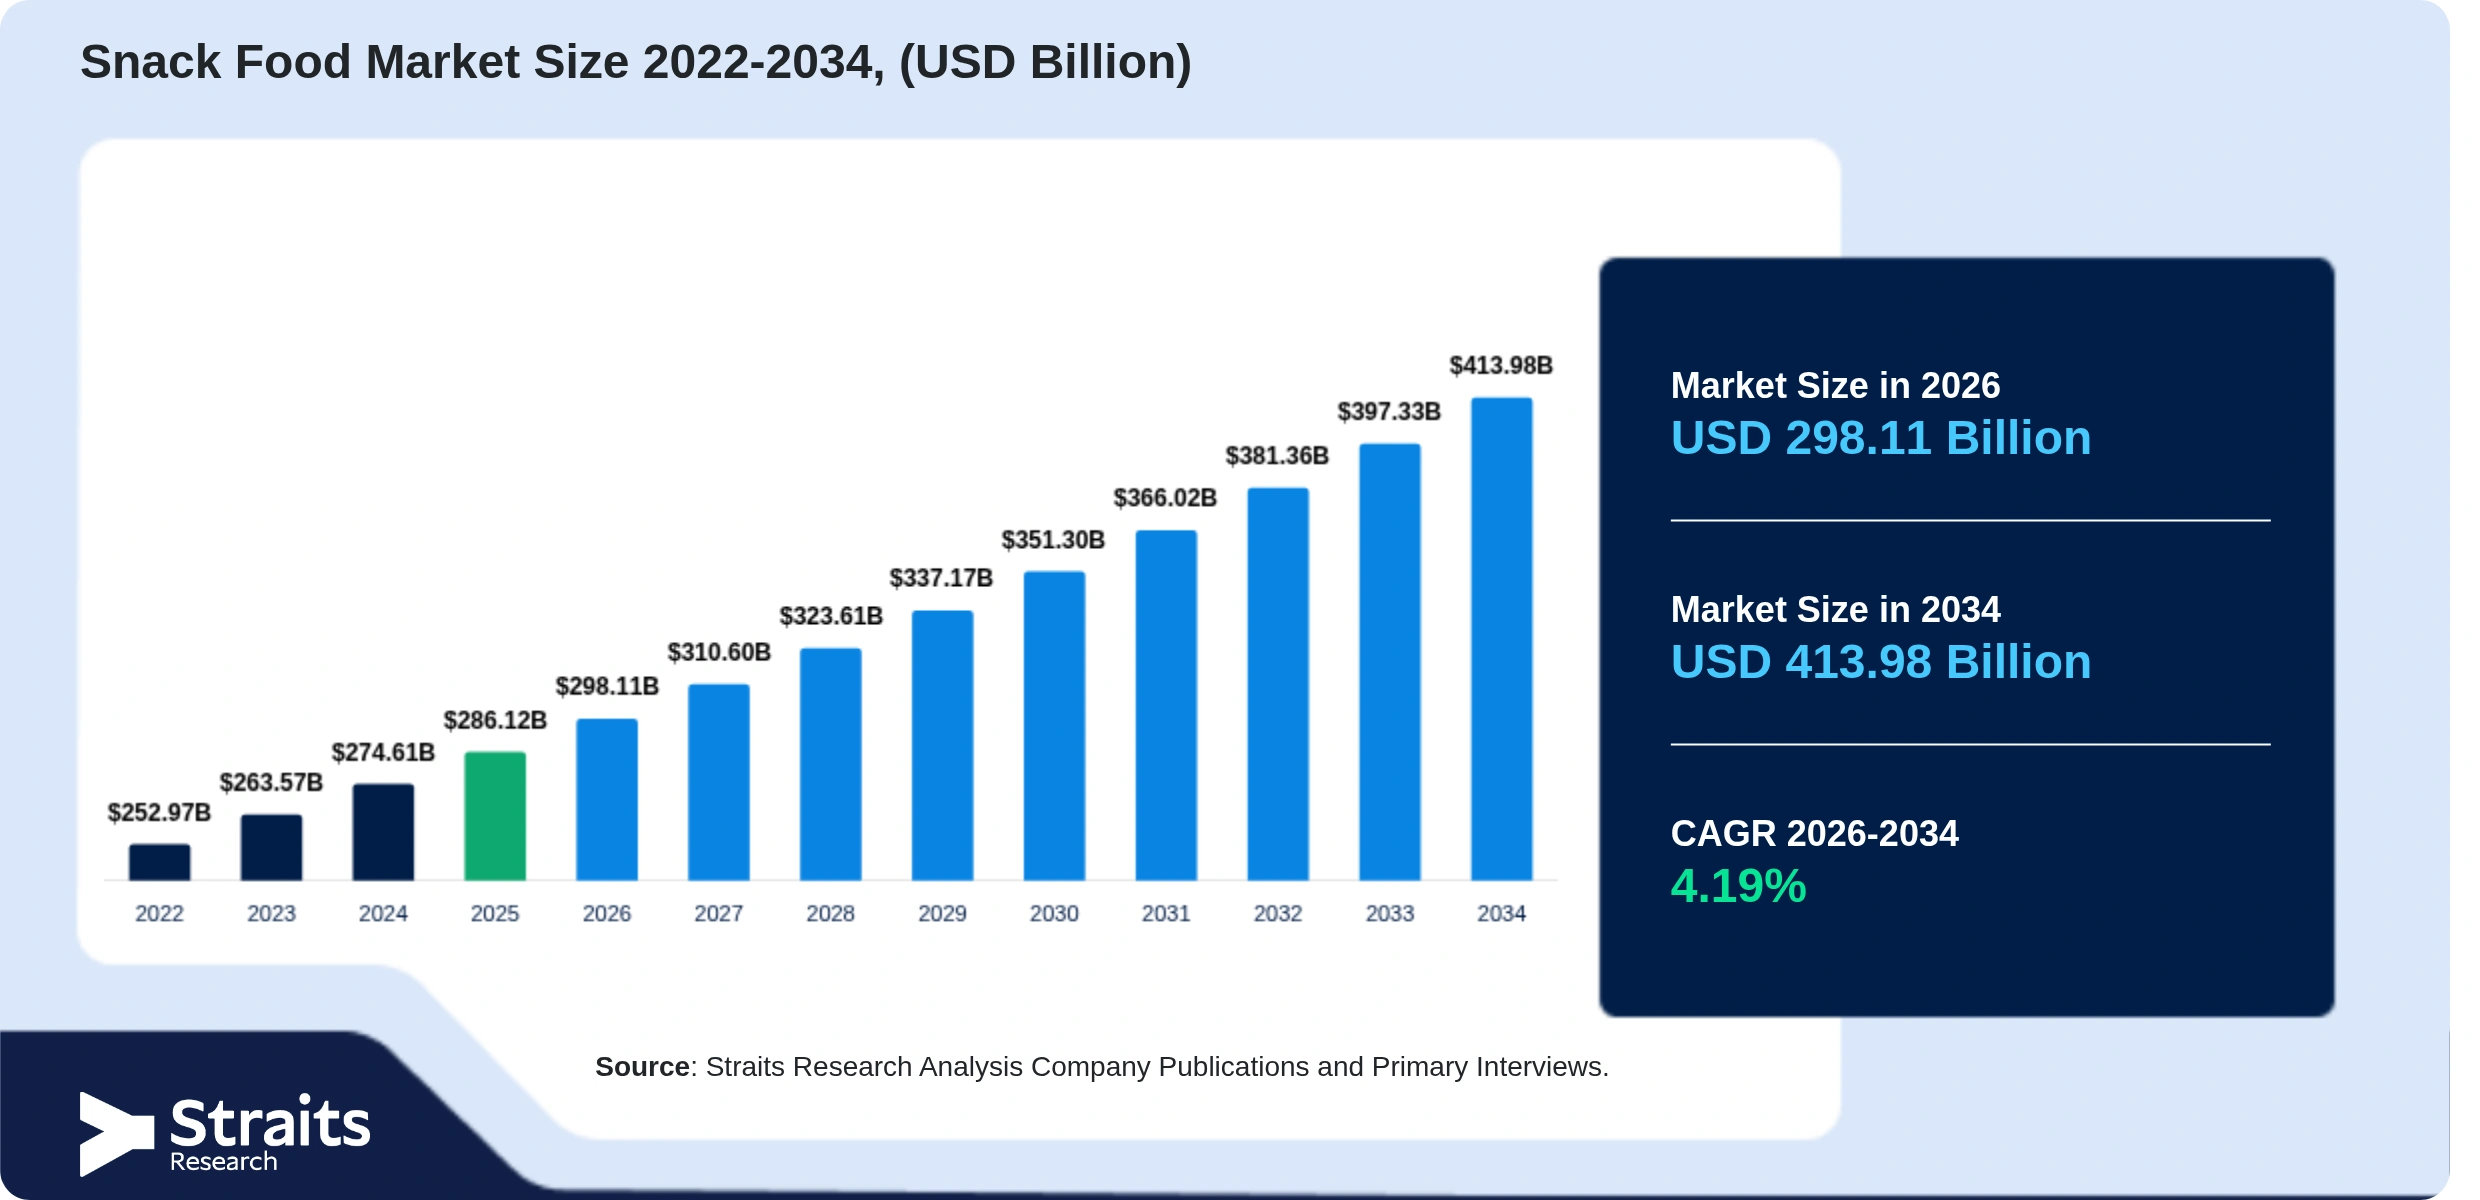
According to Straits Research, the global snack food market was valued at USD 286.12 billion in 2025 and is projected to increase from USD 298.11 billion in 2026 to USD 413.98 billion by 2034. The market is expected to register a compound annual growth rate (CAGR) of 4.19% during the forecast period from 2026 to 2034. Asia Pacific accounted for the largest regional market share in 2025, supported by changing consumption patterns and growing demand for convenient packaged foods.
Request Sample: https://straitsresearch.com/report/snack-food-market/request-sample
Market Size and Forecast
The snack food market is projected to maintain a positive growth trajectory throughout the forecast period, supported by expanding retail availability, rising on-the-go consumption, and increasing product innovation. The market's expansion reflects the continued demand for accessible food products that accommodate busy daily routines and different consumer preferences.
Key market figures include:
-
Market Size in 2025: USD 286.12 billion
-
Market Size in 2026: USD 298.11 billion
-
Projected Market Size by 2034: USD 413.98 billion
-
CAGR (2026–2034): 4.19%
-
Base Year: 2025
-
Historical Period: 2022–2024
-
Forecast Period: 2026–2034
The market is also evolving through the expansion of healthier snack options, innovative flavor combinations, and packaging formats designed for portability and portion control. These developments are creating opportunities for established manufacturers and emerging brands to serve a broader range of snacking occasions.
Market Drivers
Expansion of Modern Retail Channels
The expansion of supermarkets, hypermarkets, and convenience stores is improving the availability of packaged snack products. Wider retail networks and increased shelf space allow manufacturers to reach more consumers and distribute products across multiple purchasing environments. Dedicated snack aisles, promotional displays, and broader product assortments help improve visibility for chips, biscuits, snack bars, and other packaged foods.
The development of modern retail channels supports product accessibility and strengthens distribution opportunities for manufacturers. As retail networks expand, companies can reach different consumer groups and increase the availability of convenient snack options.
Rising On-the-Go Consumption
Changing lifestyles and busy daily schedules are increasing demand for portable foods that require little or no preparation. Urban workers, students, and travelers often prefer packaged snacks that can be carried and consumed during commuting, work breaks, and travel.
Single-serve chips, crackers, and packaged nuts provide convenient options for consumers seeking quick snacks throughout the day. This demand is encouraging manufacturers to expand their portable product offerings and develop packaging formats suited to individual consumption.
Market Challenges
Health Concerns About Salt, Sugar, and Fat Content
Health concerns associated with high levels of salt, sugar, and fat are creating challenges for conventional snack products. Consumers seeking healthier diets may reduce their consumption of traditional snacks or shift toward alternatives with lower sugar, reduced fat, cleaner ingredients, and improved nutritional profiles.
These changing preferences can limit demand for certain conventional snack categories. Manufacturers must respond to evolving consumer expectations while maintaining product taste, quality, affordability, and convenience.
Raw Material Price Volatility and Supply Chain Disruptions
Snack manufacturers depend on agricultural ingredients such as potatoes, corn, grains, and edible oils, as well as packaging materials. Price fluctuations influenced by weather and commodity-market conditions can increase production costs, pressure profit margins, and complicate pricing decisions.
Supply chain disruptions can also affect the availability of ingredients and packaging. Transportation delays, shipping interruptions, and dependence on imported materials may disrupt production schedules and make it more difficult for manufacturers to maintain consistent product availability.
Market Opportunities
Growth of Snack Subscription Services
Subscription-based snack delivery services provide opportunities for recurring revenue and stronger customer retention. Snack brands, specialty food companies, and direct-to-consumer retailers can use regular product shipments to maintain ongoing customer relationships and introduce consumers to new products.
These services can also help businesses tailor product selections to customer preferences, encourage repeat purchases, and establish more predictable revenue streams.
Expansion of Premium and Artisanal Snacks
Growing consumer interest in distinctive ingredients, innovative flavors, craftsmanship, and elevated product experiences is creating opportunities in premium and artisanal snack categories. Manufacturers can differentiate their offerings through specialized product ranges, distinctive ingredients, and higher-value positioning.
Established companies and specialty retailers can expand into premium categories to reach consumers seeking differentiated snacking experiences. These products can provide opportunities for premium pricing and broader product diversification.
Demand for High-Protein and Functional Snacks
High-protein and functional snacks are becoming increasingly important as consumers seek convenient ways to incorporate additional nutritional benefits into their daily routines. Protein bars, roasted legumes, fortified snacks, and products containing added fiber or probiotics illustrate the growing variety of functional snack options.
Manufacturers that develop products combining convenience with specific nutritional benefits can respond to changing consumer preferences and expand their presence in healthier snack categories.
Market Segmentation
The snack food market is segmented by type, distribution channel, and packaging.
By Type
The market includes savory snacks, sweet snacks, and healthy snacks. Savory snacks dominated the market in 2025, accounting for 48.6% of the total market share. Their broad consumer appeal, diverse product offerings, and suitability for frequent snacking occasions support their leading position.
The healthy snacks segment is expected to grow at a CAGR of 9.18% during the forecast period. Rising health consciousness and increasing demand for nutritious, convenient snack options are supporting the segment's growth.
Manufacturers are also incorporating international flavors into established snack formats. Flavors such as Korean barbecue, Mexican chili-lime, Japanese wasabi, and Indian masala are being introduced across chips, nuts, crackers, and extruded snacks to appeal to consumers seeking variety and new taste experiences.
By Distribution Channel
Distribution channels include supermarkets and hypermarkets, convenience stores, online retail, specialty stores, and other channels.
Supermarkets and hypermarkets held a 43.2% share of the market in 2025, supported by extensive product availability, convenience, and established retail networks. These outlets provide manufacturers with opportunities to reach a wide consumer base through broad product assortments and promotional activities.
Online retail is projected to grow at a CAGR of 10.26% during the forecast period. Increasing e-commerce adoption, convenient home delivery, and access to a diverse range of snack products are supporting online sales. Convenience stores and specialty stores also contribute to market distribution by serving different shopping occasions and consumer needs.
By Packaging
The packaging segment comprises bulk packaging, single-serve packaging, and multi-pack packaging.
Single-serve packaging accounted for 46.7% of the market in 2025, reflecting its convenience, portability, and suitability for on-the-go consumption. The segment is projected to grow at a CAGR of 7.49% during the forecast period as consumers continue to seek portion-controlled products and convenient snack formats.
Bulk and multi-pack packaging remain relevant for household consumption, value-oriented purchases, and larger-volume snacking occasions. The availability of different packaging formats enables manufacturers to address varied purchasing preferences and consumption patterns.
Regional Analysis
Asia Pacific
Asia Pacific dominated the global snack food market in 2025, accounting for 36.8% of the regional market share. Urbanization, income growth, changing household structures, and evolving food consumption patterns are supporting demand for convenient and diversified packaged food products.
In Japan, an ageing population creates opportunities for convenient, portion-controlled, and health-oriented snacks. In China, consumer product innovation and changing consumption formats provide a favorable environment for packaged snack consumption. South Korea's increasing number of one-person households also supports demand for single-serve and ready-to-eat products.
India's organized consumer-food industry is expected to record sales growth of 13–15% in fiscal 2026, with snacks and ready-to-eat or ready-to-cook products identified as important growth segments. These developments reinforce the region's importance in the global snack food market.
North America
North America is expected to be the fastest-growing regional market, registering a CAGR of 7.68% from 2026 to 2034. Population growth and changing consumer requirements are contributing to demand for convenient packaged foods and snacks.
In the United States and Canada, demographic developments are creating opportunities for products designed around convenience, portion control, and health-oriented preferences. Manufacturers can respond by expanding their product portfolios and developing snack formats suited to different consumer groups.
Europe
Europe accounted for 23.1% of the global snack food market in 2025. Population trends and demographic ageing are supporting opportunities for convenient, portion-controlled, and health-oriented snack products.
The United Kingdom's projected population growth may expand the potential consumer base for packaged snacks. In Germany and France, an ageing population creates opportunities for products that emphasize convenience and nutritional considerations. These trends encourage manufacturers to adapt their product offerings to evolving regional consumer needs.
Key Players
The global snack food market is fragmented, with participation from multinational food companies, established snack brands, regional manufacturers, private-label producers, and specialty businesses. Competition is influenced by brand recognition, product variety, taste, quality consistency, pricing, distribution networks, packaging, and product development capabilities.
The key players in the snack food market include:
-
PepsiCo Inc.
-
Kellogg Company
-
Nestlé SA
-
General Mills Inc.
-
Mondelēz International
-
Conagra Brands Inc.
-
Link Snacks Inc.
-
Unilever
Other participants include Blue Diamond Growers, Clif Bar & Company, and Dairy Farmers of America Inc.
Established manufacturers compete through extensive retail distribution, production scale, strong brand portfolios, and relationships with retailers and distributors. Emerging and specialty brands differentiate themselves through innovative flavors, healthier ingredients, premium offerings, digital marketing, sustainable packaging, and direct-to-consumer sales channels.
Recent industry developments also demonstrate continued product innovation and portfolio expansion. In July 2026, The Hershey Company introduced Reese's Pieces with Chocolate Cookie nationwide in the United States. In June 2026, PepsiCo and Subway Canada launched Lay's Italian Herbs & Cheese Flavoured Potato Chips. In December 2025, Mars completed its approximately USD 35.9 billion acquisition of Kellanova, adding several established snack brands to its global portfolio.
Conclusion
The global snack food market is projected to grow from USD 298.11 billion in 2026 to USD 413.98 billion by 2034, registering a CAGR of 4.19% during the forecast period. Growth is supported by expanding modern retail channels, rising demand for portable snack products, increasing interest in functional foods, and the introduction of innovative flavors and packaging formats.
Asia Pacific remains the leading regional market, while North America is expected to register the fastest regional growth. Savory snacks and single-serve packaging hold leading positions in their respective segments, while healthy snacks and online retail present significant growth opportunities. At the same time, health concerns, raw material price volatility, and supply chain disruptions remain important challenges for manufacturers.
Businesses that respond to changing consumer preferences, develop differentiated product portfolios, strengthen distribution capabilities, and explore premium and functional snack categories will be better positioned to compete in the evolving market.
Report Link: https://straitsresearch.com/report/snack-food-market

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
