Mobile Gaming Market Set for Strong Growth Through 2034
Mobile Gaming Market Size, Share, Trends and Forecast, 2026–2034
Market Overview
The global mobile gaming market is experiencing strong growth as smartphones, mobile internet connectivity, and accessible gaming applications continue to expand opportunities for players and developers. Mobile gaming includes playing video games on smartphones and tablets through downloaded applications, online platforms, and cloud gaming services. The market encompasses monetization models such as in-app purchases, paid applications, and advertising, alongside a broad range of gaming genres and platforms.
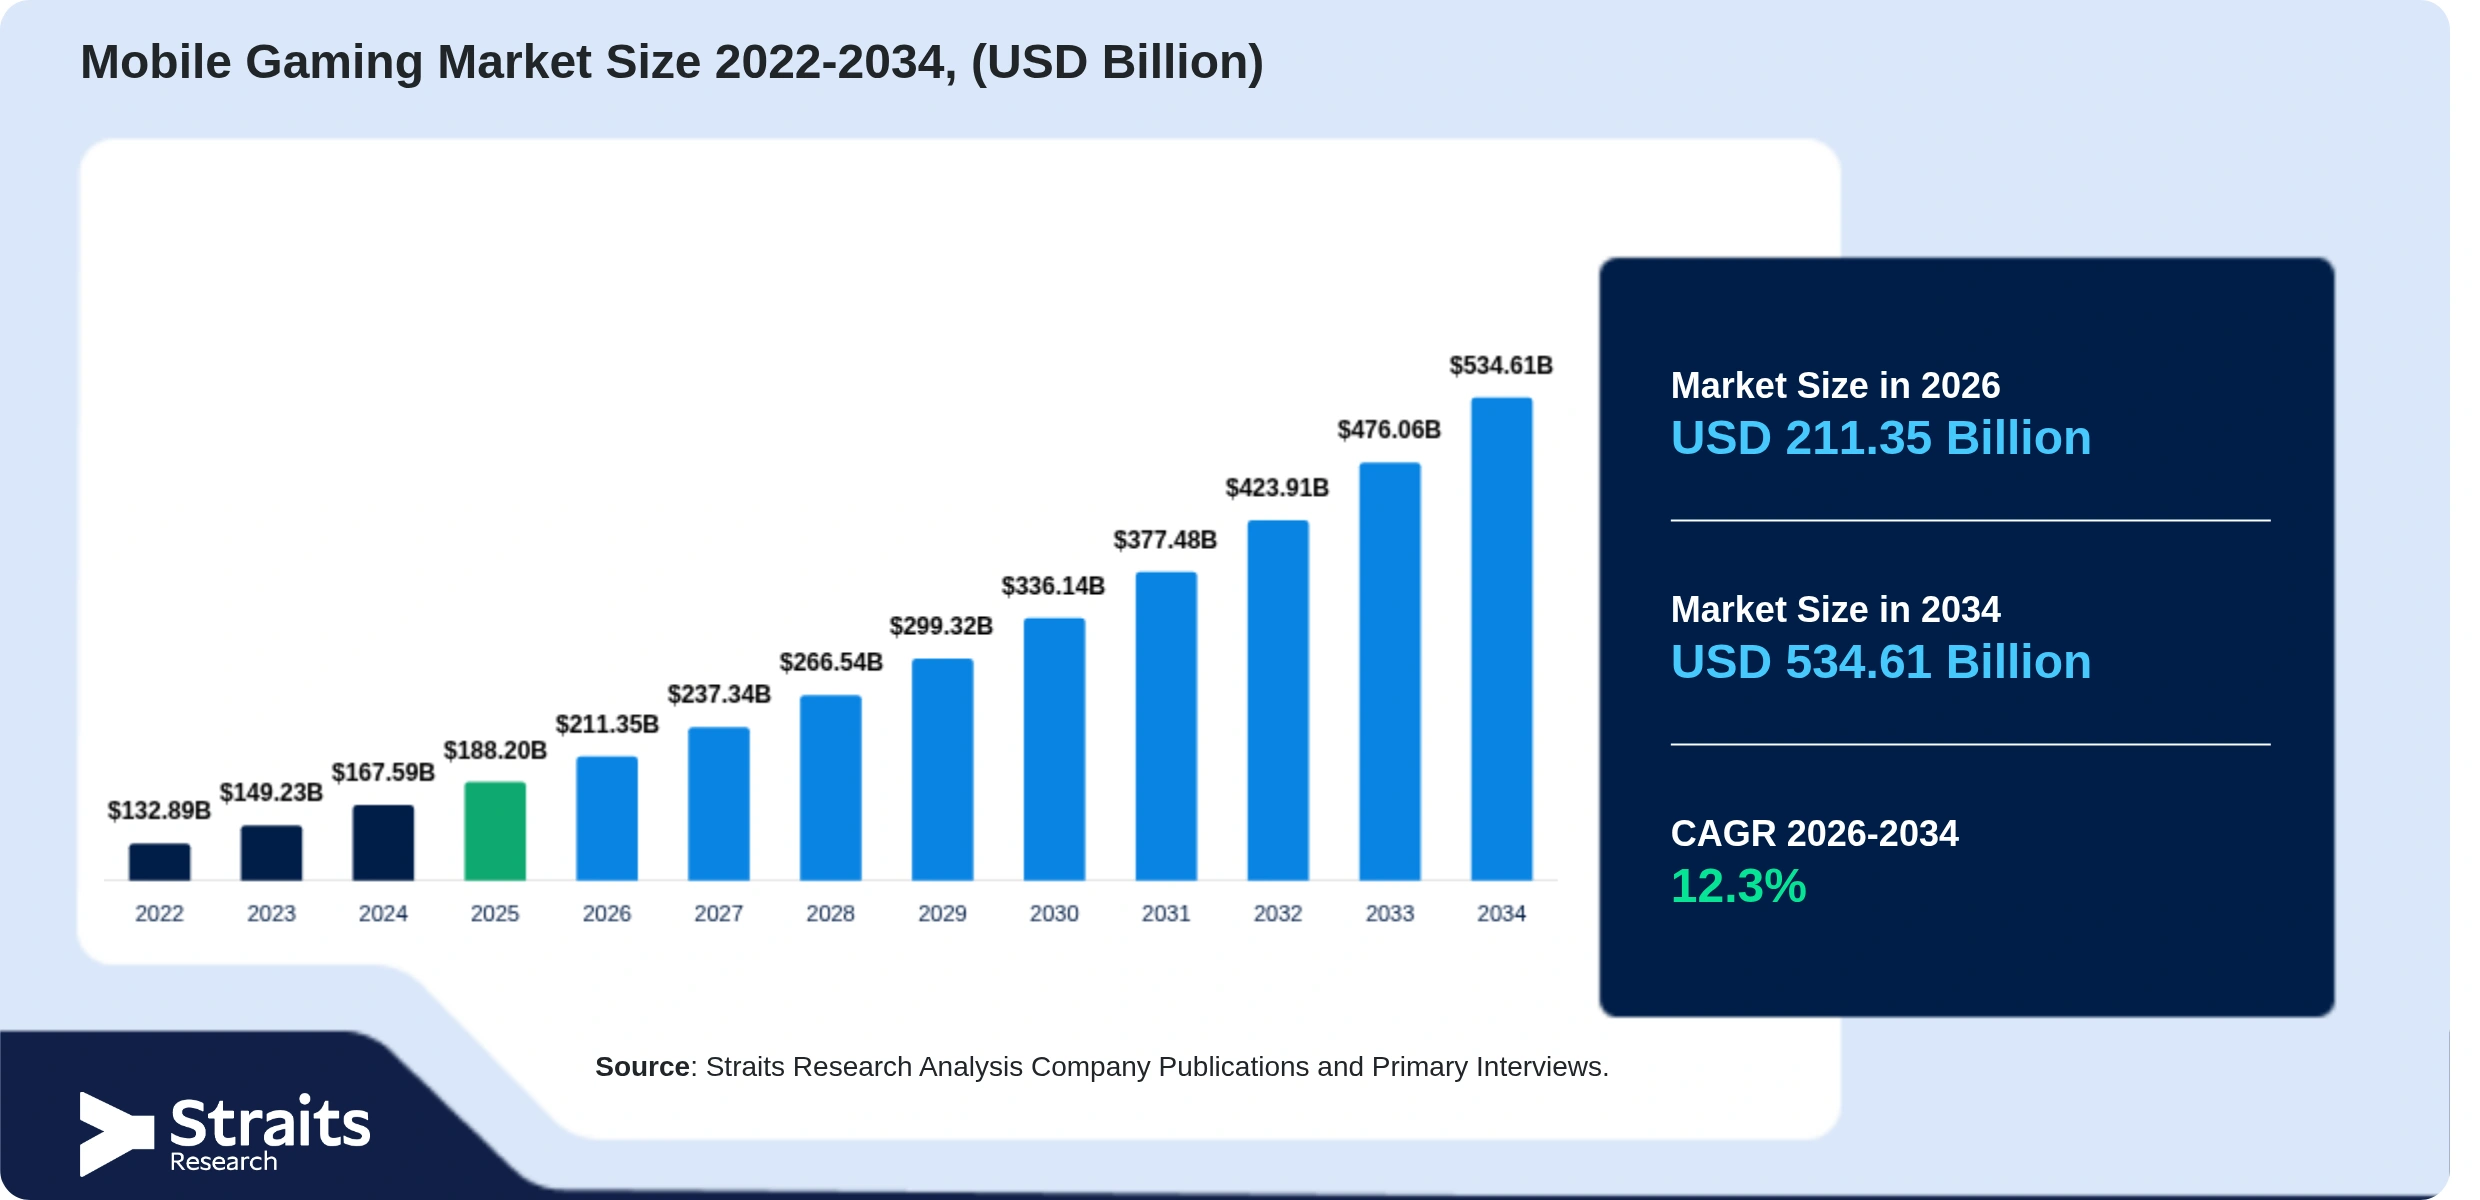
The global mobile gaming market was valued at USD 188.2 billion in 2025 and is projected to reach USD 534.61 billion by 2034, growing at a CAGR of 12.3% from 2026 to 2034. Asia Pacific led the market in 2025, accounting for 48.6% of the global share. Increasing smartphone adoption, expanding gaming communities, AI-driven personalization, and new monetization opportunities are shaping the industry's development.
Request Sample: https://straitsresearch.com/report/mobile-gaming-market/request-sample
Market Size and Forecast
The mobile gaming market is projected to grow from USD 211.35 billion in 2026 to USD 534.61 billion by 2034, reflecting a CAGR of 12.3% during the forecast period. Its growth is supported by broad smartphone accessibility, recurring in-game spending, and the expansion of advertising-supported gaming models.
In-app purchases accounted for 61.5% of the market in 2025, demonstrating the importance of virtual goods, upgrades, and premium content in generating revenue. Smartphones represented 78.4% of the market, while Android captured 61.8%. Non-money games held a 75.2% share, reflecting the popularity of gaming experiences that do not require monetary participation.
North America is expected to be the fastest-growing regional market, with a projected CAGR of 13.42% between 2026 and 2034. These market developments highlight the opportunities available to game publishers, developers, advertising providers, and gaming technology companies.
Market Drivers
Smartphone Adoption Expands Gaming Access
Growing smartphone adoption is increasing access to mobile games across different age groups and income levels. Affordable devices and wider internet connectivity allow consumers to enjoy games without purchasing dedicated gaming hardware. Casual games, including puzzle and racing titles, offer convenient entertainment during short breaks and commutes. This expanding user base supports game downloads and demand for new mobile gaming content.
In-App Purchases Strengthen Revenue Generation
In-app purchases create recurring revenue opportunities for mobile game developers and publishers. Players can purchase virtual currency, character upgrades, cosmetic items, and premium features to enhance their gaming experiences. These purchases help developers finance new content, maintain existing titles, and introduce additional features. The segment's 61.5% market share in 2025 highlights its importance to the industry's monetization strategies.
Market Challenges
Intense Competition Limits Game Visibility
The large number of mobile games makes it difficult for new titles to stand out in app stores. Limited discoverability can increase promotional costs and restrict player acquisition. Smaller developers may struggle to establish a sustainable user base and achieve profitability.
Data Privacy Rules Restrict Targeted Advertising
Data privacy regulations limit how developers collect and use player information for advertising and user tracking. Reduced targeting accuracy can make audience acquisition less efficient. These restrictions may increase marketing costs and constrain advertising revenue.
Market Opportunities
Cloud Gaming Creates New Revenue Streams
Cloud gaming offers opportunities for developers, service providers, and telecommunications companies to deliver high-quality gaming without requiring large downloads or powerful local hardware. Potential revenue sources include subscriptions, premium game access, and partnerships with mobile network operators. Companies such as NVIDIA and Microsoft are active in cloud gaming services.
Cross-Platform Gaming Expands Player Communities
Cross-platform gaming enables players to connect across smartphones, computers, and consoles. Compatibility across devices can expand gaming communities, encourage continued participation, and improve retention. Game sales, subscriptions, downloadable content, and licensing partnerships offer potential revenue opportunities. Companies such as Epic Games and Microsoft support cross-platform gaming ecosystems.
Market Segmentation
By Monetization Type
In-app purchases led the segment with a 61.5% share in 2025, supported by spending on virtual goods, upgrades, and additional content. The advertising segment is projected to grow at a CAGR of 11.52%, driven by rewarded video advertisements, in-game advertising, and ad-supported free-to-play games. Paid applications remain another monetization option.
By Device Type
Smartphones accounted for 78.4% of the market in 2025, supported by widespread adoption, portability, and access to gaming applications. The smartphone segment is projected to grow at a CAGR of 12.36% during 2026–2034. Tablets offer larger displays and enhanced gameplay experiences, with the segment expected to grow at a CAGR of 8.96%.
By Gaming Vertical
Non-money games represented 75.2% of the market in 2025, reflecting broad accessibility and demand for entertainment-focused games. The segment is projected to grow at a CAGR of 11.32%. Money games are expected to expand at a CAGR of 13.68%, supported by interest in competitive formats involving monetary rewards or stakes.
By Genre
Casual games accounted for 27.6% of the market in 2025, benefiting from accessible gameplay, short sessions, and broad appeal. Action and adventure games are expected to record the fastest growth among the highlighted genres, with a projected CAGR of 12.86%. Other categories include strategy, puzzle, sports, educational, arcade, and roleplaying games.
By Platform
Android held a 61.8% share in 2025, supported by its broad device base, multiple price points, and extensive game selection. The iOS segment is projected to grow at a CAGR of 10.96%, supported by continued user engagement and its established app distribution ecosystem. Other third-party stores also contribute to game distribution.
Regional Analysis
Asia Pacific
Asia Pacific dominated the mobile gaming market with a 48.6% share in 2025. The region's market outlook reflects its substantial mobile gaming audience and ongoing digital infrastructure development. In Japan, targets for expanded 5G and fibre-optic coverage could strengthen access to connected gaming services. China's connectivity plans and India's targets for extending 5G and optical-fibre access may also support broader participation in online and cloud gaming.
North America
North America is projected to be the fastest-growing regional market, with a CAGR of 13.42% from 2026 to 2034. Connectivity investment in the United States and Canada may improve access to online multiplayer games, cloud gaming, and graphics-intensive mobile experiences. These developments create potential opportunities for publishers and service providers seeking to expand their audiences.
Europe
Europe accounted for 18.7% of the mobile gaming market in 2025. Connectivity improvements and the expansion of digital entertainment services support the region's gaming outlook. In the United Kingdom, plans to extend standalone 5G coverage could improve access to responsive multiplayer and cloud gaming. Germany's broadband coverage targets may also support game downloads and online play in rural communities.
Key Players
The mobile gaming market is fragmented, with global publishers, mobile-first studios, independent developers, and regional gaming companies competing across different genres and monetization models. Key and emerging players include:
-
Supersonic Studios Ltd.
-
Rollic Games Oyun Yazılım ve Pazarlama Anonim Şirketi
-
Ascella Mobile
-
CrazyLabs Ltd.
-
SayGames Ltd.
-
Outfit7 Limited
-
Tencent Holdings Limited
-
Nintendo Co., Ltd.
Other notable companies include Activision Blizzard, Zynga, GungHo Online Entertainment, Electronic Arts, Kabam Games, Rovio Entertainment, NCSoft, Ubisoft, NetEase, Glu Mobile, and Reliance Games.
Competition is shaped by game portfolio diversity, player engagement, intellectual property, gameplay quality, monetization strategies, marketing budgets, and distribution channels. Smaller developers often focus on distinctive concepts, niche genres, frequent content updates, and community-driven features to attract and retain players.
Recent industry developments include Tencent Games' April 2026 launch of an AI-powered game development platform featuring intelligent non-player characters, personalized gameplay, and cloud-based optimization tools. In February 2026, Supercell introduced a new global multiplayer mobile game while expanding its live-service platform with AI-driven engagement and personalization features.
Conclusion
The mobile gaming market is projected to grow significantly, rising from USD 211.35 billion in 2026 to USD 534.61 billion by 2034 at a CAGR of 12.3%. Smartphone adoption, in-app purchases, advertising-supported games, and evolving gaming experiences are central to this outlook. In-app purchases remain the leading monetization model, while smartphones and Android hold substantial market shares. Asia Pacific currently leads the market, and North America is expected to register the fastest regional growth.
Cloud gaming, cross-platform compatibility, and AI-driven personalization offer additional avenues for developers and publishers to expand engagement and diversify revenue. However, competition for player attention and restrictions on data-driven advertising remain important challenges. Companies that develop compelling games, improve retention, and adapt their monetization approaches will be positioned to pursue opportunities in this evolving market.
Report: https://straitsresearch.com/report/mobile-gaming-market
 Spanish
 English
 Arabic
 French
 Portuguese
 Deutsch
 Turkish
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
