Why PVC and Polyurethane Are Shaping the Construction Plastic Market
Construction Plastic Market: Size, Share, Trends, and Growth Forecast
Market Overview
The global construction plastic market is expanding as residential, commercial, and infrastructure projects increasingly incorporate durable, lightweight, and corrosion-resistant materials. Construction plastics include polymer-based products such as PVC pipes, insulation materials, plastic flooring, roofing membranes, window frames, fittings, and other building components. Their ease of installation, moisture resistance, and durability make them suitable for a wide range of construction applications.
The market is supported by growing construction activity, expanding electrical and telecommunication infrastructure, and rising demand for efficient building materials. The increasing use of plastic products in plumbing, insulation, flooring, roofing, and cable protection also strengthens their role in modern construction projects.
Request Sample: http://straitsresearch.com/report/construction-plastic-market/request-sample
Market Size and Forecast
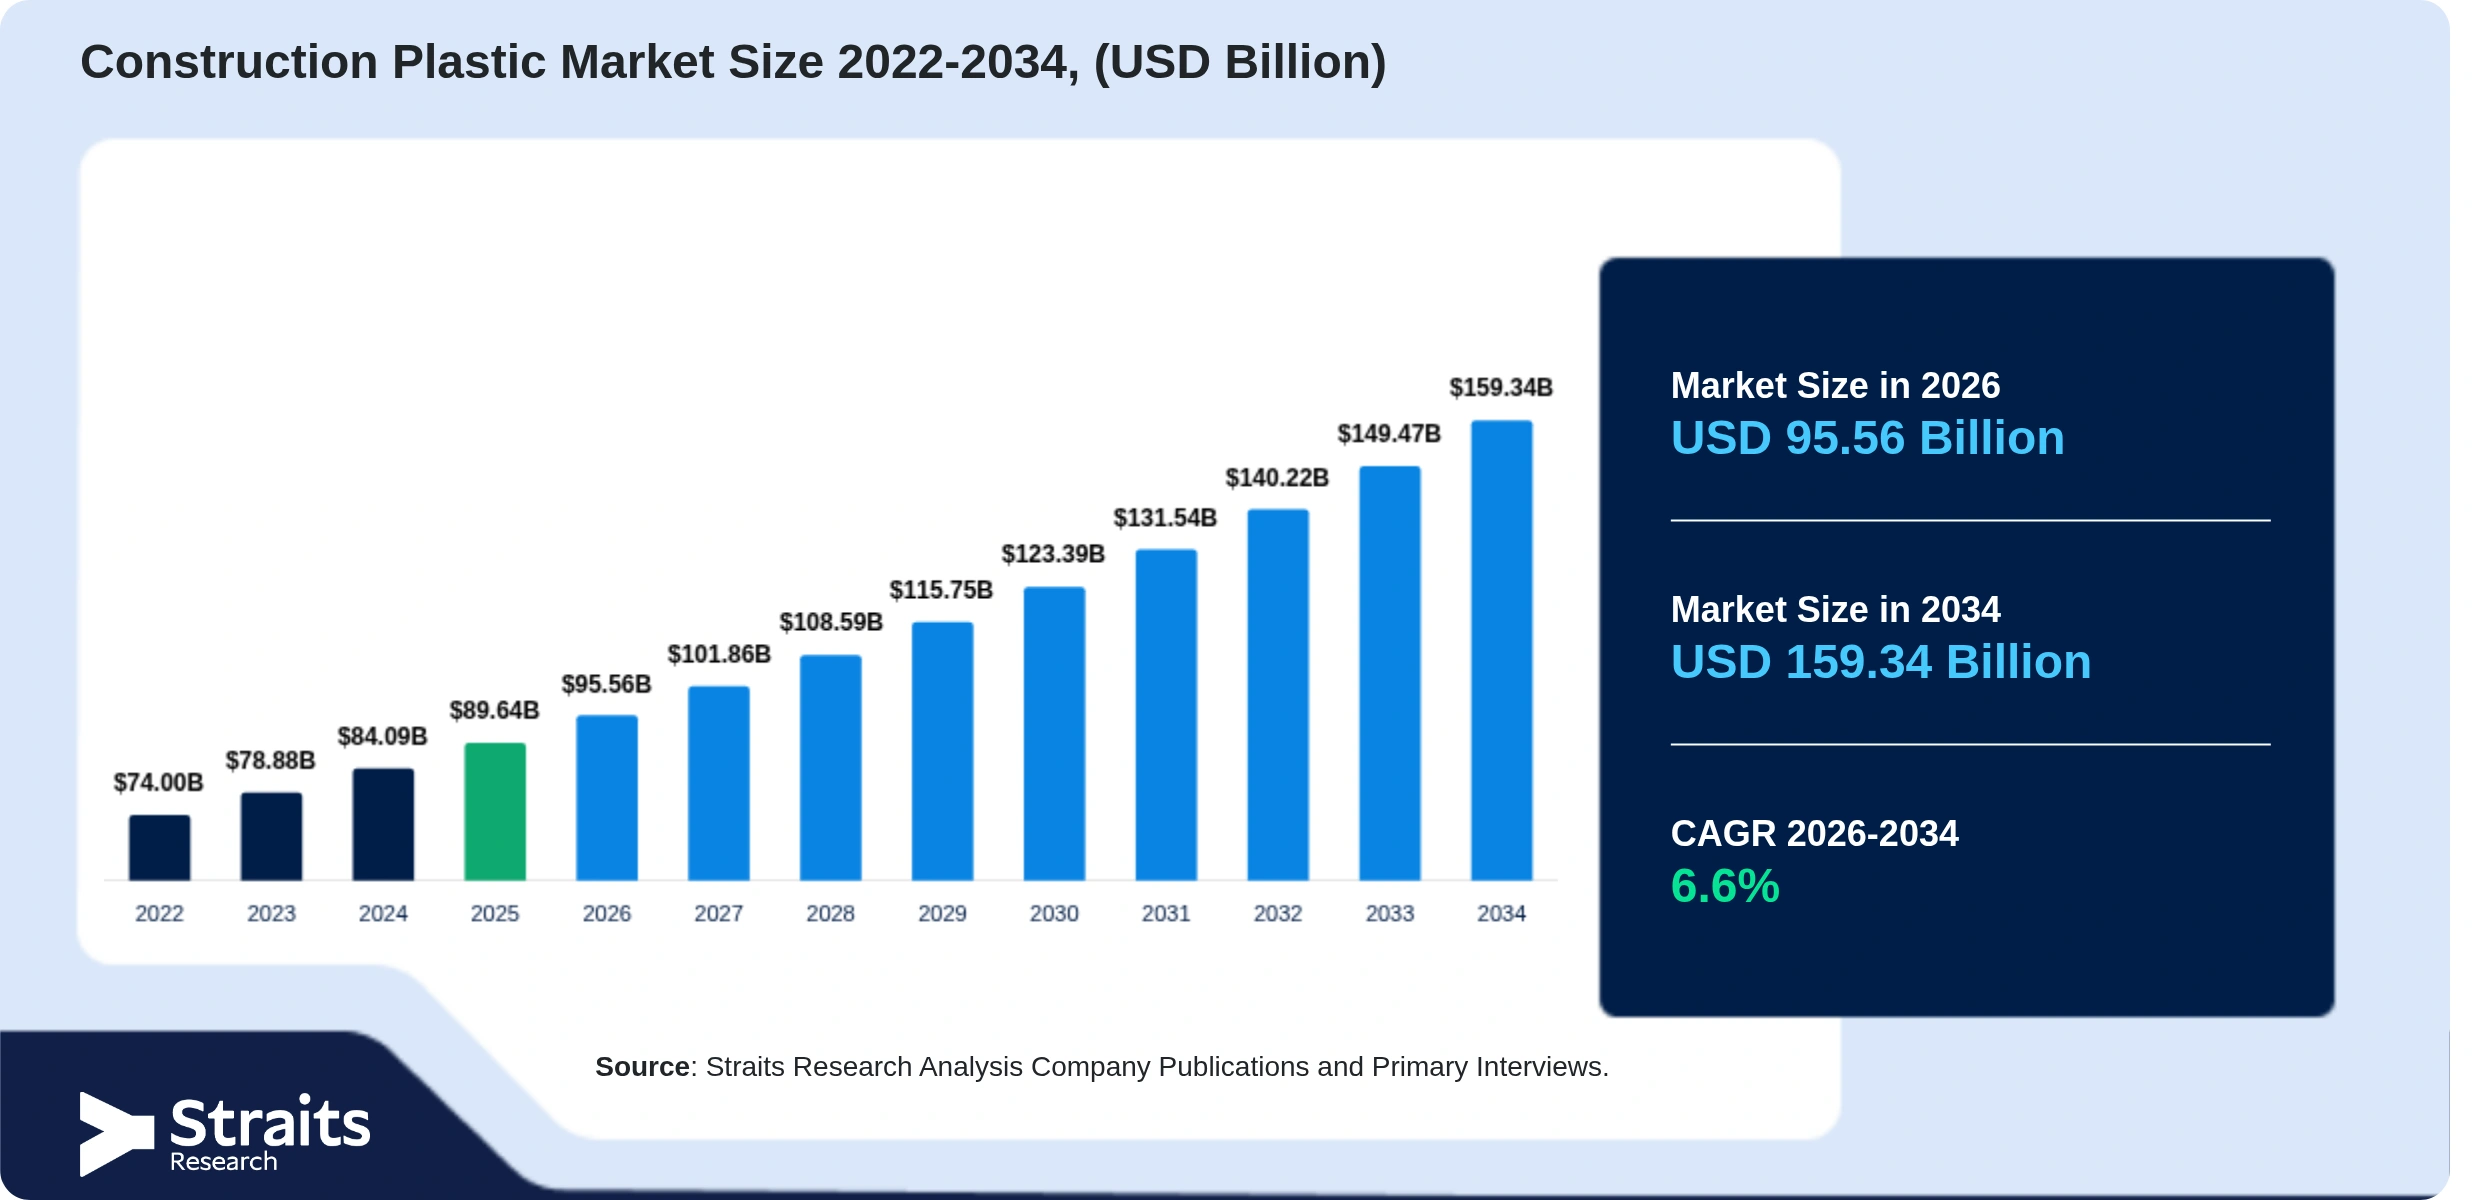
The global construction plastic market was valued at USD 89.64 billion and is projected to increase from USD 95.56 billion to USD 159.34 billion over the forecast period. The market is expected to register a compound annual growth rate (CAGR) of 6.6%.
Asia Pacific holds the largest regional position, accounting for 42% of the global market. Meanwhile, North America is projected to be the fastest-growing region, with a CAGR of 7.8%. Increasing construction activity and infrastructure development across major economies are supporting the market's expansion.
Market Drivers
Expansion of Residential and Commercial Construction
Growing residential and commercial construction activity is increasing demand for plastic products used in plumbing, flooring, roofing, insulation, doors, and window systems. Housing developments, office complexes, and shopping centers require substantial quantities of plastic building materials for installation and finishing. PVC pipes, plastic water tanks, and window profiles are widely used in residential apartment projects, supporting procurement across manufacturers and distributors.
Growth in Electrical and Telecommunication Infrastructure
The expansion of power distribution and telecommunication networks is creating demand for plastic materials used to protect cables and electrical components. Plastic conduits, cable ducts, junction boxes, and protective enclosures provide insulation, corrosion resistance, and installation convenience. Underground power cable installations, for example, use HDPE ducts to protect cables from moisture and physical damage.
Rising Demand for Prefabricated Construction Components
The growing adoption of modular buildings and prefabricated structures is creating demand for plastic panels, fittings, insulation components, and installation accessories. Standardized construction processes encourage bulk procurement of ready-to-install products, supporting opportunities for manufacturers supplying specialized construction plastics.
Market Challenges
The supplied market information does not identify specific market restraints or quantify their impact on industry growth. However, manufacturers operate in a competitive environment where product quality, material performance, production capacity, pricing, and customized product offerings influence their market position. Established companies compete through product performance and manufacturing capabilities, while emerging participants focus on competitive pricing and flexible production.
Market Opportunities
Growing Demand for Energy-Efficient Insulation
Insulation represents the fastest-growing application segment, with a projected CAGR of 7.2%. Increasing demand for energy-efficient buildings and effective thermal insulation materials creates opportunities for manufacturers of polyurethane products and other construction plastics. Polyurethanes are also expected to record a CAGR of 7.4%, supported by their use in insulation, sealants, and energy-efficient building materials.
Infrastructure Development in Emerging Economies
Investments in water supply, sanitation, drainage, and urban infrastructure are creating opportunities for plastic piping and related construction materials. China's plans to build and upgrade approximately 770,000 km of urban underground pipelines, supported by an earmarked investment of RMB 160 billion, provide substantial opportunities for plastic pipes and fittings.
India also presents opportunities through housing and water infrastructure programs, alongside the expected addition of approximately 3 million tonnes of domestic PVC capacity. Improved resin availability could support downstream manufacturers supplying lightweight and corrosion-resistant construction products.
Market Segmentation
By Product
Polyvinyl chloride (PVC) dominated the product segment, accounting for 32% of the market. Its widespread use in pipes, fittings, flooring, and other construction applications, along with its durability, cost-effectiveness, and moisture resistance, supports its leading position. Polyurethanes are projected to grow at a CAGR of 7.4%, driven by demand for insulation, sealants, and energy-efficient building materials.
By Application
Pipes and ducts held the largest application share of 38%, supported by their extensive use in water supply, drainage, sewage, and ventilation systems. Insulation is projected to register a CAGR of 7.2%, driven by increasing demand for energy-efficient buildings and effective thermal insulation materials.
By End User
Non-residential construction accounted for the largest end-user share of 50%. Demand is supported by investments in commercial buildings, industrial facilities, and infrastructure projects. Residential construction is projected to grow at a CAGR of 6.5%, driven by urbanization, housing development, and renovation activities. Plastic products used in plumbing, insulation, window frames, and interior finishes continue to support demand across residential projects.
Regional Analysis
Asia Pacific
Asia Pacific dominated the construction plastic market, accounting for 42% of the global share. Infrastructure renewal in Japan is supporting demand for plastic pipes, insulation, flooring, and other construction materials. China's urban underground pipeline development plans are creating opportunities for plastic piping products. In India, expected additions to domestic PVC capacity and continued housing and water infrastructure programs are supporting downstream demand.
North America
North America is projected to be the fastest-growing regional market, registering a CAGR of 7.8%. Infrastructure investments in the United States across transportation, water systems, buildings, and energy are expected to sustain demand for plastic pipes, insulation, and roofing materials. In Canada, investments through the Build Communities Strong Fund and Build Canada Homes are creating additional opportunities for construction plastic suppliers.
Europe
Europe accounted for 22% of the global construction plastic market. The United Kingdom's infrastructure pipeline and affordable housing commitments are expected to support demand for building materials. Germany's infrastructure and climate-neutrality special fund, covering investments in roads, railways, waterways, housing, and hospitals, also provides opportunities for construction plastic applications.
Key Players
The construction plastic market is moderately fragmented, with participation from global polymer manufacturers, diversified chemical companies, and specialized plastic product manufacturers. DowDuPont, BASF SE, and Asahi Kasei are estimated to account for 38% of the global market share. Companies compete through product quality, material performance, production capacity, competitive pricing, and customized solutions.
Key companies operating in the market include:
-
DowDuPont (US)
-
BASF SE (Germany)
-
Asahi Kasei Corporation (Japan)
-
LyondellBasell Industries Holdings B.V. (Netherlands)
-
Borealis AG (Austria)
-
Solvay S.A. (Belgium)
-
Saudi Basic Industries Corporation (SABIC) (Saudi Arabia)
-
Berry Plastics Corporation (US)
Conclusion
The construction plastic market is positioned for continued growth as residential and commercial construction, infrastructure development, and demand for lightweight building materials support product adoption. PVC continues to lead the product segment, while insulation offers strong growth potential. Asia Pacific remains the largest regional market, whereas North America is expected to record the fastest growth.
The expansion of infrastructure networks, increasing use of prefabricated components, and demand for energy-efficient building materials are expected to create opportunities for manufacturers across the construction plastic value chain.
 Turkish
 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Dutch
 Italiano
 Russian
 Romaian
 Portuguese (Brazil)
 Greek
